Picture supply: Domino’s Pizza Group plc
It wouldn’t be an exaggeration to name the UK market a dividend inventory investor’s dream. It’s residence to actually tons of of revenue shares, lots of that are providing yields of 5% or extra.
Listed below are two shares — one from the FTSE 100 and the opposite the FTSE 250 — that I reckon have the potential to ship common revenue and share worth progress on high. They’re each yielding above 6% on a forward-looking foundation.
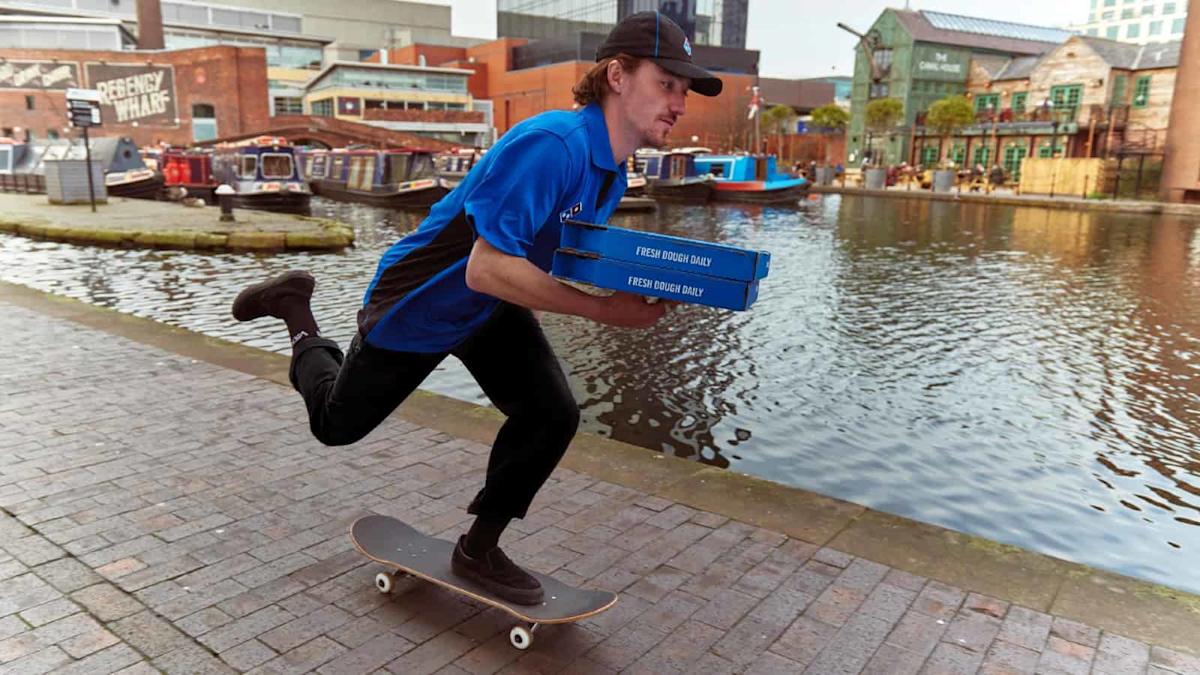
Domino’s Pizza Group (LSE:DOM) has had a horrible 2025, plunging 45%. And this implies the FTSE 250 pizza inventory is now 62% decrease than it was in the beginning of 2022. Ouch.
This displays sluggish progress and ongoing margin strain on the UK grasp franchise of the Domino’s model. Consequently, the dividend has been a bit all over, falling from 14.7p per share in 2020 to 10p in 2022 then rising to 11p final 12 months.
Given the weak shopper setting, this isn’t a inventory with out danger. In November, administration warned that “the robust working setting is more likely to proceed to affect order counts into 2026“.
Nevertheless, whereas difficult, issues do seem like stabilising, with Q3 complete system gross sales up 2.1% and like-for-like system gross sales up 1%. For the complete 12 months, administration saved its steerage for underlying EBITDA of £130m-£140m. Dividends ought to proceed.
In the meantime, the corporate says its Chick ’N’ Dip provide has began properly within the North West of England and Northern Eire. It might be rolled out throughout all shops in 2026, and the agency is continuous to evaluate alternatives for the acquisition of a second model to kickstart progress.
The inventory seems low cost at 9.4 instances ahead earnings, whereas there’s a 6.3% ahead dividend yield on provide. This could possibly be one to take a look at extra carefully for its turnaround potential, I really feel.
Subsequent up is Aviva (LSE:AV.), which is the polar reverse of Domino’s Pizza Group. 12 months so far, the FTSE 100 insurance coverage inventory has surged 44%.
Over 5 years, Aviva has greater than doubled!
But regardless of this enormous run, Aviva continues to be sporting a gorgeous 6.1% ahead dividend yield. And given administration’s bullishness on the course of the enterprise, traders may be set for some robust revenue progress.
The outlook for Aviva has by no means been higher. The benefits of our diversified enterprise, 25m robust buyer base, and majority capital-light earnings, imply we count on to ship an increasing number of for our shareholders and prospects. CEO Amanda Blanc
Aviva now expects its enterprise to be over 75% capital-light by the top of 2028. This implies it’s going to use much less capital to ship progress, which bodes properly for dividends and share buybacks.
That mentioned, a UK recession would pose challenges for Aviva, particularly if it was extreme sufficient to trigger households and companies to instantly tighten their belts.
As issues stand although, the inventory seems first rate worth, buying and selling at 11.5 instances subsequent 12 months’s earnings. Placing this along with the 6.1% yield, share buybacks resuming subsequent 12 months, in addition to the current Direct Line acquisition, and I feel Aviva continues to be price contemplating.
The submit 2 passive revenue shares providing dividend yields above 6% appeared first on The Motley Idiot UK.
Extra studying
Ben McPoland has positions in Aviva Plc. The Motley Idiot UK has really useful Domino’s Pizza Group Plc. Views expressed on the businesses talked about on this article are these of the author and subsequently could differ from the official suggestions we make in our subscription providers comparable to Share Advisor, Hidden Winners and Professional. Right here at The Motley Idiot we imagine that contemplating a various vary of insights makes us higher traders.
Motley Idiot UK 2025
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/