Picture supply: Getty Photos
The FTSE 100’s residence to loads of high-yielding dividend shares. And with so many to select from, it will probably generally be difficult to know the place to start out. In the present day (12 January), 13 of them supply a yield better than 5%.
However amongst all these fascinating alternatives, this inventory seems to me to be one of the promising proper now. Let’s take a more in-depth look.
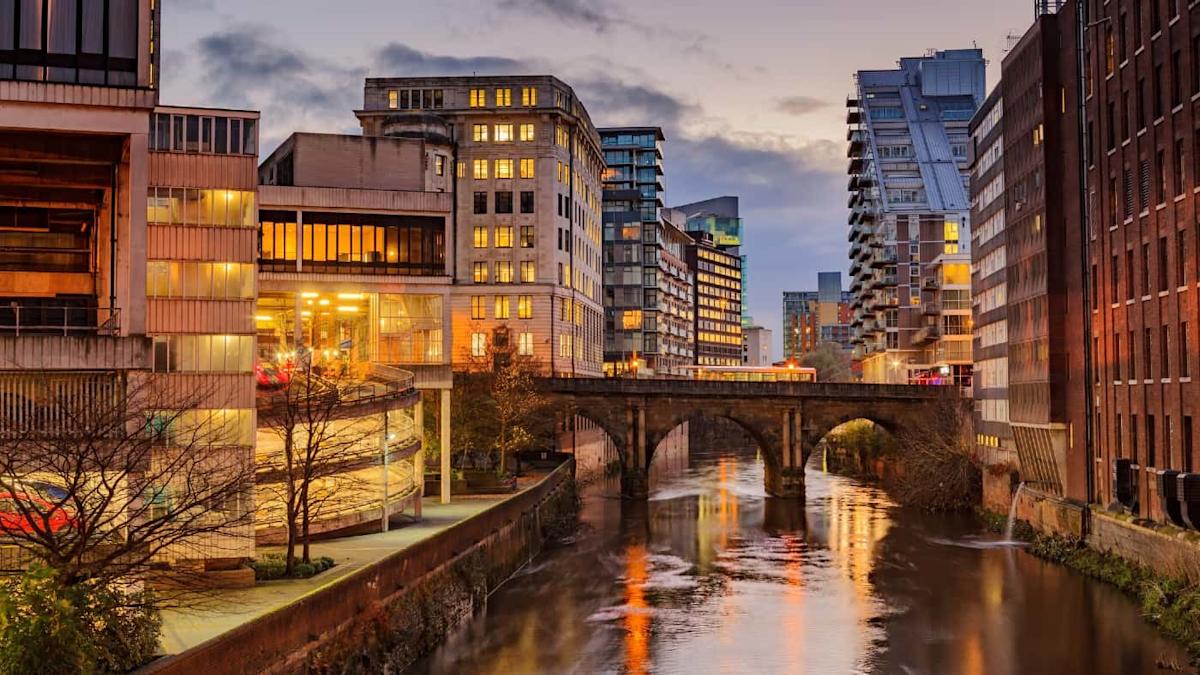
Because of excessive occupancy charges within the workplaces and retailers that it owns, Land Securities Group (LSE:LAND) has been steadily rising its returns to shareholders lately.
Primarily based on its dividend for the yr ended 31 March 2025 (FY25) of 40.4p, and a present share value of 640p, the inventory’s presently yielding 6.3%. At this degree of return, an investor would wish to spend slightly below £16,000 on the group’s shares to realize an annual passive revenue of £1,000.
Nevertheless, I think most individuals don’t have this quantity of spare money mendacity round. However I reckon it’s attainable to get there over time. For instance, shopping for 16 shares every week for 3 years might generate an revenue stream from dividends of £1,000 within the fourth yr.
This assumes the payout stays unchanged. In fact, the group’s unable to supply any ensures that this would be the case.
Nevertheless, Land Securities has elevated its FY26 interim dividend by 2% this yr. Analysts predict a full-year payout of 41.3p, rising by 7% to 44.2p by FY28.
With an occupancy charge of 97.7%, it’d seem tough to extend earnings sufficiently to cowl the upper forecast dividend. Nevertheless, over the subsequent 5 years, the group’s planning to promote £2bn of its workplaces and make investments £2bn+ in residential properties. It sees the sector as providing “larger revenue progress” alternatives and “much less cyclicality”.
It additionally owns some prestigious developments, together with Liverpool One and Media Metropolis in Salford, which implies it’s in a position to improve rents by greater than inflation. In the course of the first half of FY26, it claims to have achieved a ten% uplift on re-lettings and renewals.
However at 8.6 instances EBITDA (earnings earlier than curiosity, tax, depreciation, and amortisation), the group’s debt stays excessive. Though it hopes to scale back this beneath seven inside two years, this makes its earnings weak to rates of interest staying larger for longer than anticipated. A loan-to-value of 40.3% (at 30 September 2025) provides some consolation however I feel its degree of borrowings is one thing to look at intently.
Personally, I feel the group’s in good condition. Its portfolio of flagship properties provides it some safety from the cyclical nature of the UK business property sector. And helps it outperform its two nearest rivals, Unibail-Rodamco-Westfield and Hammersonwith regards to retail footfall and occupancy ranges.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/