Key Factors
- A vocal group of SAVE debtors say they will not change reimbursement plans till pressured, hoping a pending lawsuit or one other twist rewards those that stayed put.
- The one energetic lawsuit, Havens v. U.S. Division of Schooling, would not ask to increase SAVE or the forbearance, reasonably it asks the court docket to revive the older REPAYE plan — which means even a borrower victory would restart funds, at quantities increased than SAVE.
- The ready itself has a operating value: roughly $3,500 per yr in curiosity for the everyday borrower, plus months of no direct progress towards forgiveness.
Formal 90-day notices started going out to greater than 7 million SAVE debtors on July 1, arriving in waves. Debtors who do not select a brand new reimbursement plan by their deadline (roughly September 30 for the primary group) will probably be positioned on the Normal plan routinely.
In response, a standard chorus has emerged in remark sections and boards: “I refuse to modify till I am notified I’ve to. That manner, if any new court docket motion advantages SAVE debtors, it should nonetheless apply to me as a result of I am technically nonetheless registered beneath SAVE.”
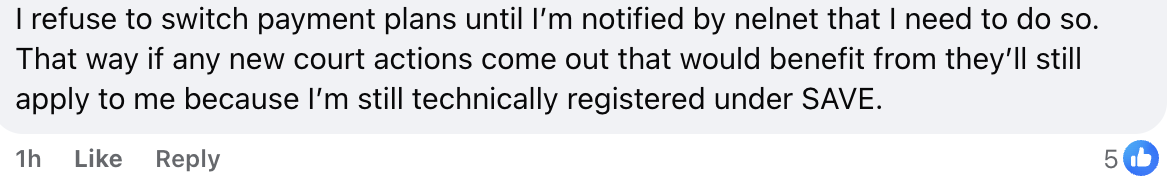
This consists of some organizations which can be encouraging their members to not take motion:
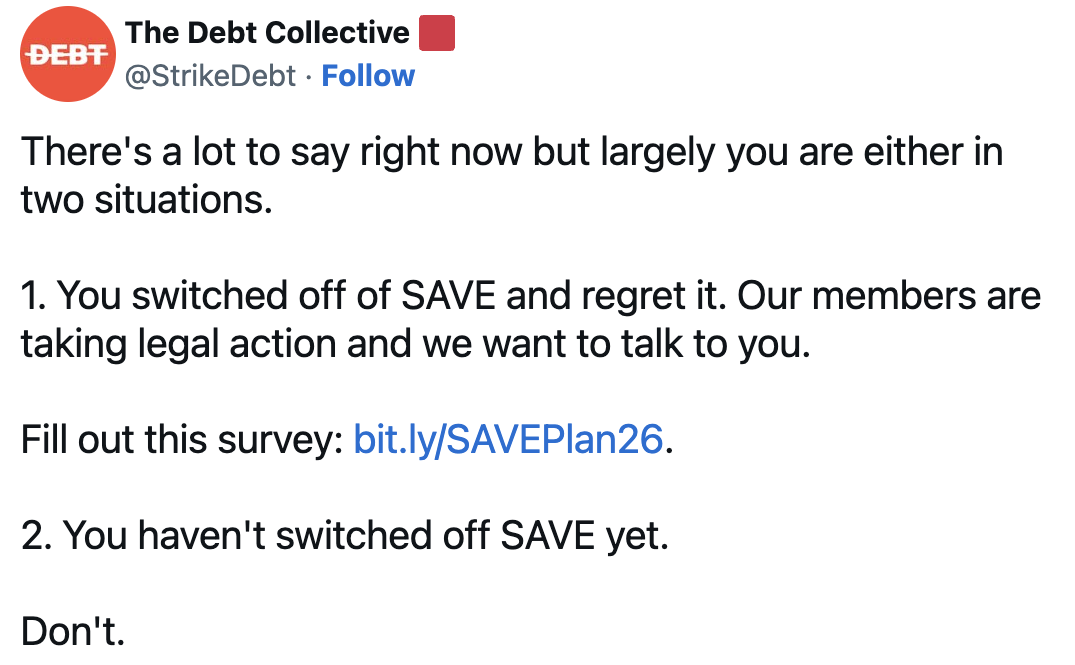
It makes it sound like ready within the SAVE forbearance may very well be a sensible transfer.
However whenever you stroll by way of each situation that would truly unfold (the pending lawsuit, a forbearance extension, and the even longer-shot wildcards) the technique delivers nearly nothing completely different that switching would not additionally ship, whereas the prices of ready improve each month.
The straightforward fact is that ready solely preserves your no-payment forbearance. Your mortgage steadiness is rising, you are not making progress in the direction of forgiveness, and the longer you wait, the extra doubtless you’re to have even increased funds sooner or later.
Here is what to learn about every situation and the way it may affect you as a SAVE borrower desirous about ready it out.
Would you want to avoid wasting this?
We’ll e-mail this text to you, so you may come again to it later!
State of affairs 1: The Havens Lawsuit Wins And Ends The SAVE Forbearance Anyway
The one energetic authorized effort standing between debtors and the transition deadline is Havens v. U.S. Division of Schooling. This court docket case is not new – it began again in March. However with the timelines beginning to transfer debtors out of SAVE, the plaintiffs have filed extra motions to try to get an injunction.
Here is what most debtors banking on this case misunderstand: the plaintiffs are usually not asking to “save” SAVE. Their argument is that when the courts vacated the SAVE rule in March, the prior regulation (REPAYE, the reimbursement plan SAVE was constructed on) ought to have been restored.
They contend the Division’s refusal to manage REPAYE is a “shadow repeal” carried out with out the required rulemaking, and that involuntarily transferring debtors with out the choice for REPAYE exceeds the Division’s statutory authority.
Observe that logic to a win, and the end result surprises the wait-and-see crowd.
If the court docket orders the Division to permit REPAYE, debtors may enroll within the plan. The REPAYE plan required funds for 20 years for undergrads and 25 years for graduate debtors. The cost was 10% of discretionary earnings, utilizing 150% of the poverty line. That is the next cost than SAVE for almost everybody.
The three issues that would occur:
- Profitable ends the SAVE forbearance. Permits REPAYE till 2028.
- Dropping is the established order, with SAVE forbearance nonetheless ending.
- Potential forbearance persevering with whereas the court docket case occurs, however provided that the choose points an injunction (which hasn’t occurred but).
Simply as essential: the aid requested is a keep of the company’s actions, not only a aid for these enrolled in SAVE. Meaning, if this case wins, everybody has entry to REPAYE till 2028. You do not have to be within the SAVE forbearance to get the profit.
One named plaintiff is not enrolled in something related — his declare is that he cannot apply to REPAYE. If REPAYE have been restored as an choice, a borrower who already switched to IBR or PAYE may apply proper again into it till it ends in 2028.
The chances: The case has been pending since March with none injunctive aid, and the Division argues a D.C. court docket can’t override the Missouri court docket’s last judgment that ended SAVE. Earlier challenges over SAVE and REPAYE went nowhere whereas the state-led challenges that dismantled the plan succeeded.
Here is the the professionals and cons of ready on the end result of this lawsuit:
Professionals
Cons
State of affairs 2: The Forbearance Will get Prolonged
An extension is believable — not due to any court docket, however due to logistics. Servicers are working by way of 7 million debtors needing to alter reimbursement plans, doubtless between now and March 2027.
However take a look at what an extension truly delivers: extra months of forbearance throughout which curiosity accrues and nothing counts towards forgiveness.
This is identical situation debtors have been on since 2024, and lots of are worse off in consequence.
Here is the the professionals and cons of ready on to see if the forbearance is prolonged:
Professionals
Cons
State of affairs 3: The Wildcards
Retroactive credit score for forbearance months. If any court docket order or future administration ever grants forgiveness credit score for time within the SAVE forbearance, eligibility would relaxation on having been within the forbearance (a reality completely recorded in federal mortgage knowledge) not on remaining in it. The IDR account adjustment labored precisely this fashion, crediting previous intervals primarily based on mortgage historical past whatever the borrower’s present plan.
So, leaving now would finish the SAVE forbearance, but additionally resuming funds will get you credit in the direction of forgiveness. This can be a tremendous lengthy shot, however you would argue that you have value your self a number of months of funds you would not have needed to make, on the danger of it persevering with to develop your mortgage with no profit.
A future Congress or administration revives a beneficiant plan. Any new statute or regulation would set its personal eligibility guidelines. The one actual grandfathering in present regulation (entry to IBR, PAYE, and ICR) relies on having loans disbursed earlier than July 1, 2026, not on SAVE enrollment.
Entry to reimbursement plans relies on mortgage origination date, not being enrolled in a selected plan.
And the earliest we may see huge change once more is 2030. This assumes that in 2029 and Presidency modifications in addition to each the Home and Senate – and that they work over the summer time to cross huge reform that would take impact in 2030.
Here is the the professionals and cons of ready on both of those wildcard outcomes:
Professionals
Cons
Ready Has A Value
Curiosity on SAVE loans resumed August 1, 2025. Eleven months later, the everyday affected borrower has added roughly $3,200 to $3,500 to their steadiness, primarily based on Pupil Borrower Safety Heart estimates (PDF File) of about $300 monthly.
The forgiveness value is much less seen however usually bigger. Not one of the forbearance time counts towards IDR forgiveness, and it counts towards PSLF solely by way of the buyback program — which gives no low cost for these months and carries a multi-year processing queue.
A PSLF borrower who waited from August 2025 by way of September 2026 gave up 14 qualifying months. And when you’re shopping for again, your funds at this time in 2026 are precisely the identical value as reimbursement can be. For somebody inside a number of years of forgiveness, that delay can truly improve prices sooner or later.
For these going for time-based mortgage forgiveness, future funds are more likely to be costlier. That signifies that both you are going to pay extra lifetime, and/or scale back future mortgage forgiveness.
The profit is what most debtors are targeted on: no funds due.
Staying put does shield your short-term money stream — actual aid when you’re dealing with hardship. However it converts at this time’s respiratory room into a bigger steadiness, an extended clock, and a riskier deadline. As The Faculty Investor’s SAVE resolution framework places it:
- In case your aim is forgiveness, you want the most cost effective qualifying months that rely.
- In case your aim is payoff, you wish to repay the smallest quantity legally allowed.
The forbearance accomplishes neither – and makes each eventualities costlier for you over time.
Backside Line
In the event you run each situation ahead, the identical reply retains coming again: staying in SAVE forbearance is not more likely to profit you financially long-term.
The pathways on the desk (together with those the Havens plaintiffs are literally asking for) both apply to switchers and stayers alike, or are primarily based in your cost historical past that is already on report.
The one profit ready is that you haven’t any cost due. However this selection would not change the long-term math of a rising mortgage steadiness. Each month within the forbearance provides roughly $300 in curiosity for the everyday borrower and strikes nobody nearer to forgiveness.
Debtors pursuing PSLF or IDR forgiveness ought to change now and restart the clock, utilizing The Faculty Investor’s Pupil Mortgage Calculator to match funds. For many debtors pursuing PSLF, the aim is the bottom month-to-month cost between IBR, PAYE, and RAP.
And for households that really cannot afford a cost, the forbearance stays a official hardship instrument — simply deal with it as that, not as a long run technique, and calendar the deadline so you do not find yourself in Normal plan unexpectedly.
Do not Miss These Different Tales:
@media (min-width: 300px){(data-css=”tve-u-19f34574b50″).tcb-post-list #post-58271 (data-css=”tve-u-19f34574b56″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2025/05/Depositphotos_154366650_XL-150×150.jpg”) !essential;}}
SAVE Pupil Mortgage Plan Timeline Estimates: What To Count on
SAVE Pupil Mortgage Plan Timeline Estimates: What To Count on@media (min-width: 300px){(data-css=”tve-u-19f34574b50″).tcb-post-list #post-76955 (data-css=”tve-u-19f34574b56″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2025/12/Schooling-Secretary-Linda-McMahon-150×150.jpg”) !essential;}}
$180 Billion in Pupil Loans Are Now in Default, New Federal Knowledge Reveals
$180 Billion in Pupil Loans Are Now in Default, New Federal Knowledge Reveals@media (min-width: 300px){(data-css=”tve-u-19f34574b50″).tcb-post-list #post-77357 (data-css=”tve-u-19f34574b56″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2026/03/Instructor-In-a-Classroom-150×150.jpg”) !essential;}}
PSLF Technique in 2026: New Employer Rule, RAP Plan, and Father or mother PLUS Adjustments
PSLF Technique in 2026: New Employer Rule, RAP Plan, and Father or mother PLUS Adjustments
Editor: Colin Graves
The publish Staying In SAVE Forbearance Has Value Debtors $3,500 Every — Right here’s What Each State of affairs Prices appeared first on The Faculty Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/