Private finance recommendation has a guilt downside. Someplace alongside the best way, shopping for a espresso turned an ethical failure and carrying any debt in any respect turned a personality flaw. The web is stuffed with folks apologizing for utterly regular cash conduct.
However right here’s the factor. When precise monetary planners discuss what sinks folks, virtually none of it’s the stuff you’re feeling dangerous about. Numerous the “errors” on this listing barely register to them, and some are issues planners quietly do themselves.
So listed here are 31 cash sins you’ll be able to cease confessing, counting right down to the one piece of guilt that’s costing folks essentially the most.
31. Shopping for Lunch at Work Generally
Meal prepping seven days per week is principally a part-time job, and the individuals who declare to adore it are mendacity a minimum of just a little. Packing lunch most days and shopping for it when the week falls aside is what sustainable truly seems to be like.
The all-or-nothing model fails the identical manner crash diets do. One busy Tuesday breaks the streak, guilt kicks in, and the entire behavior collapses. Most days selfmade, some days purchased. That’s a system that survives actual life.
30. Not Studying Each Private Finance Guide
There are tons of of cash books, and folks really feel behind for not having learn them. Right here’s a secret from inside that world. They largely say the identical 5 issues time and again.
Spend lower than you earn, automate your financial savings, put money into low-cost index funds, insure towards disasters, don’t panic-sell. That’s it, that’s the style. One good e-book covers it. The opposite ninety-nine are the identical recommendation sporting completely different covers.
29. Not Realizing Your Credit score Rating to the Precise Level
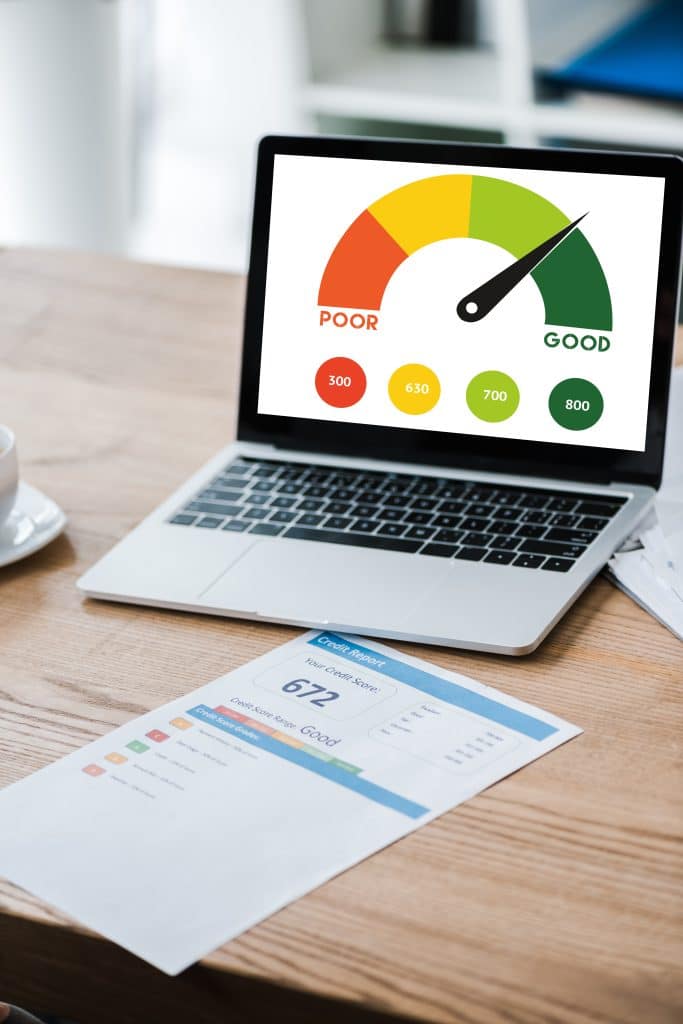
Some folks test their rating weekly prefer it’s a inventory ticker, then really feel just a little jolt of disgrace each time it wiggles 5 factors. These wiggles imply virtually nothing.
Pay your payments on time and hold your card balances low, and the rating takes care of itself. A tough sense of your vary, checked just a few instances a yr, is genuinely all the eye it wants. Obsessing modifications nothing besides your stress stage.
28. Retail Remedy in Small, Contained Doses
A deliberate forty greenback deal with after a brutal month shouldn’t be a spending downside, it doesn’t matter what the frugality boards say. Deliberate, budgeted, achieved. That’s simply spending cash on goal, which is allowed.
What planners truly fear about is the unconscious model. The scrolling-at-midnight purchases you don’t bear in mind making. A contained deal with with a quantity hooked up is the other of that, and for lots of people it’s the strain valve that retains the remainder of the plan intact.
27. Shopping for Retailer-Model The whole lot Besides Your Few Favorites
Frugality purists act like several model loyalty is a weak spot. In the meantime the shop model is often made in the identical manufacturing unit because the identify model, so switching on the stuff you don’t care about is free cash.
However the reverse snobbery is foolish too. If one particular model of espresso or peanut butter genuinely makes your week higher, purchase it with out apology. Save on the ninety % you’ll be able to’t inform aside, splurge on the ten % you’ll be able to.
26. Ordering Takeout on Your Worst Weeknights
Cooking each meal from scratch is a stunning splendid that assumes you by no means have a day the place all the things goes flawed. A thirty greenback takeout order on that day isn’t a failure. Generally it’s a budget possibility.
Take into consideration what it’s truly stopping. The stress grocery run the place you purchase ninety {dollars} of random stuff. The deserted meal plan that lets a fridge filled with meals rot. Takeout as a strain valve, a pair instances a month, retains the entire cooking behavior alive.
25. Spending on Hobbies That Make Nothing
Someplace alongside the road, each interest turned a possible facet hustle, and spending cash on one thing that produces zero earnings began feeling irresponsible. That’s an odd manner to consider being alive.
A interest that prices fifty bucks a month and retains you sane, shifting, and off the procuring apps is affordable. Evaluate it to what careworn, bored folks spend as a substitute. The interest isn’t the leak. It’s normally the plug.
24. Having “Enjoyable Cash” With No Justification
Right here’s one which surprises folks. Monetary planners construct guilt-free spending cash into consumer plans on goal. A certain amount, each month, no receipts, no explanations, no judgment.
They do it as a result of plans with out it fail. A funds with zero pleasure in it really works precisely in addition to a weight loss program of plain rice, that means about three weeks. The enjoyable cash isn’t a leak within the plan. It’s a load-bearing a part of the plan.
23. Giving Cash to Household, With Limits
The recommendation world treats serving to household like a cardinal sin, and the horror tales are actual. However most planners gained’t let you know by no means to assist. They’ll let you know learn how to assist with out taking place with the ship.
The precise guidelines are easy. Assist from power, not by raiding your individual emergency fund. Set a quantity upfront and deal with it as gone, a present, not a mortgage you’ll resent. And by no means co-sign something you couldn’t cowl alone. Inside these strains, serving to your folks is okay.
22. Taking the Occasional Trip Whereas in Debt
Zero enjoyable till debt-free sounds hardcore and fails continuously. A multi-year payoff with no aid in-built doesn’t produce self-discipline. It produces a blowout, normally round month eight.
A modest, deliberate, paid-in-cash journey in the course of a protracted payoff isn’t a relapse. It’s upkeep. The households who truly end the payoff are normally those who made the journey survivable, not those who tried to white-knuckle it.
21. Shopping for New As an alternative of Used, Generally
Used-first is genuinely nice recommendation, proper up till it turns into a faith. There’s a brief listing of issues the place new is the defensible name, and no skilled will fault you for it.
Automobile seats, the place you’ll be able to’t confirm crash historical past. Mattresses and helmets, the place put on you’ll be able to’t see is the entire situation. Trainers, the place the cushioning is the product. Shopping for used is a technique, not a purity check, and security gadgets had been by no means a part of the deal.
20. Paying an Annual Price for a Credit score Card You Really Use
“By no means pay an annual price” is a type of guidelines that sounds clever and doesn’t survive contact with a calculator. The rule of thumb isn’t the purpose. The maths is the purpose.
If the rewards and credit you genuinely use add as much as greater than the price, the cardboard is paying you, full cease. The important thing phrase is genuinely. Depend what you’d use anyway, not the aspirational perks. If the mathematics works, the price is okay. In the event you’re maintaining perks you by no means contact, that’s the precise mistake.
19. Ignoring the Marketplace for Months at a Time
Folks really feel responsible for not watching their investments, just like the portfolio is a pet they’re neglecting. Humorous factor is, the neglect is the technique.
Checking day by day makes regular dips really feel like emergencies, and emergencies make folks promote on the worst doable second. The buyers who barely look, who let the boring computerized contributions run for many years, are those the checking-daily crowd finally ends up envying. Your index fund doesn’t want your supervision.
18. Not Selecting Particular person Shares
Any individual at each barbecue has a inventory story, and in the event you’re simply quietly shopping for boring index funds, it’s simple to really feel such as you’re doing the newbie model of investing. You’re not. You’re doing the model most professionals truly advocate.
Even most mavens who choose shares for a residing have a tough time beating a easy index fund over the long term, which is precisely why so lots of them hold their very own cash in funds. The barbecue man tells you about his winner. He by no means mentions the opposite 4.
17. Not Having a Aspect Hustle
Hustle tradition turned relaxation into one thing folks apologize for. In case your evenings don’t generate income, you’re apparently doing life flawed. Planners are inclined to see it in another way.
For most individuals, the highest-paying facet undertaking accessible is their primary profession. Making ready for one elevate dialog may be value extra per hour than a yr of weekend gig work, with out burning out the vitality that profession runs on. A facet hustle is an possibility, not an obligation.
16. Spending Actual Cash on a Good Mattress
Dropping 4 figures on a mattress feels indulgent proper up till you do the mathematics. You’ll spend roughly a 3rd of the following decade on it. Virtually nothing else you personal will get used eight hours a day, day-after-day, for ten years.
Break a great mattress right down to value per evening and it’s pocket change for one thing that impacts your temper, your well being, and your potential to operate on the job that pays for all the things else. Value per use, it embarrasses half the “smart” purchases in your home.
15. Paying for Comfort When You’re Busy
Grocery supply. The occasional home cleaner. Pre-chopped greens that value two {dollars} extra. The guilt round these runs deep, as a result of they really feel like paying for laziness.
Planners body it in another way. In your most disturbing seasons, you’re not shopping for laziness, you’re shopping for again hours, and hours are the one factor you’ll be able to’t earn extra of. If a supply price prevents a takeout spiral or buys you a sane Sunday, it could be essentially the most defensible line on the assertion.
14. Conserving One Splurge Class That Outsiders Would Decide
Sneakers. Live performance tickets. Fancy skincare. Board video games. Everybody has one class the place their spending seems to be insane from the surface, and most of the people carry low-grade disgrace about it.
Planners have a reputation for the wholesome model of this: values-based spending. Lower with out mercy on all the things you don’t care about, then spend overtly on the one factor you’re keen on. The folks in hassle aren’t those with one loud splurge. They’re those leaking cash evenly throughout all the things, loving none of it.
13. Shopping for Your Every day Espresso
The 5 greenback latte has taken extra blame than any buy in historical past. Run the precise numbers and it’s round 100 fifty bucks a month, which is actual however small subsequent to the selections that tower over it.
Your lease, your automobile, your wage. These are value twenty espresso habits every. Planners would a lot moderately see you benefit from the espresso and spend that guilt-energy negotiating your pay. If the latte is your funds’s largest downside, your funds doesn’t have issues. And talking of money owed everybody’s ashamed of, wait till you see quantity 8.
12. Leasing a Automobile, In Some Conditions
Leasing will get handled because the official dumbest transfer in private finance. Purchase used, drive it endlessly, finish of dialogue. And that’s the most cost-effective path, no person’s arguing.
However most cost-effective isn’t the one defensible reply. Low-mileage drivers who worth predictable prices, and enterprise homeowners with legit deductions, can land in spots the place a lease is an affordable commerce of cash for comfort. Realizing the tradeoff and selecting it anyway isn’t a mistake. It’s only a selection.
11. Spending Extra on Housing Than the Outdated Guidelines Permit
The thirty % housing rule was born a long time in the past, in a very completely different housing market. In right this moment’s costly metros, following it may be mathematically inconceivable on a traditional earnings, and folks torture themselves over it anyway.
What issues is the entire image. Going over the rule in a metropolis the place your profession truly pays, whereas maintaining vehicles and different spending lean, can beat “inexpensive” housing in a spot with no alternative. The rule is a place to begin. It was by no means an ethical regulation.
10. Not Shopping for a House in Your Twenties
“Renting is throwing cash away” could be essentially the most repeated dangerous sentence in private finance. Lease buys you one thing actual: flexibility, zero restore payments, and the liberty to chase a greater job in one other metropolis on a month’s discover.
Shopping for too early is the costly mistake no person warns you about. Transaction prices are so heavy that proudly owning briefly and promoting can torch years of would-be financial savings. Purchase when your life is steady sufficient to remain put some time, not when the strain will get loud.
9. Utilizing a Credit score Card for The whole lot
Loads of folks deal with bank cards like a vice they need to stop. However the card was by no means the issue. The steadiness is the issue.
Carrying a steadiness means brutal curiosity, and that a part of the status is earned. Utilizing a card for all the things and paying it in full every month is a unique exercise totally. You get fraud safety debit can’t match, a rising credit score rating, and rewards, all for spending cash you had been spending anyway.
8. Having Pupil Loans within the First Place
The disgrace round scholar debt runs deeper than virtually any cash matter. Folks deal with the steadiness like a scarlet letter, proof they did life flawed at eighteen.
Right here’s the reframe planners supply. If the diploma raised your incomes energy, the mortgage was an funding that largely labored, even when the worth was ugly. And both manner, the guilt modifications nothing. A payoff plan lowers the steadiness. Disgrace simply makes you keep away from taking a look at it, and avoidance is the one true mistake within the room.
7. Paying Off a Low-Curiosity Mortgage Slowly, On Objective
The debt-free-scream crowd will hate this one. In the event you’re sitting on an outdated mortgage at three %, racing to pay it off isn’t robotically sensible. It’s emotionally satisfying, which isn’t the identical factor.
Cash thrown at a 3 % mortgage is cash not incomes extra elsewhere, even in a plain high-yield financial savings account. Loads of planners carry low-cost debt on goal and put the additional money to higher use. If being debt-free helps you sleep, that’s value one thing too. However slow-paying low-cost debt is a technique, not a sin.
6. Conserving Cash in a Boring Financial savings Account
Investing tradition has folks feeling responsible about money, like each greenback not out there is a greenback being wasted. Then the automobile dies, or the job disappears, and instantly boring money is the hero of the entire story.
Emergency funds and short-term targets belong in financial savings, full cease, as a result of cash you’ll want quickly can’t be using a market dip once you want it. The one actual improve is the place the money sits. A high-yield account pays precise curiosity for a similar zero danger. Boring was at all times the purpose.
5. Carrying a Mortgage Into Retirement
For many years this was non-negotiable. You don’t retire with a mortgage, interval. Your grandparents burned the paperwork within the yard and invited the neighbors.
The maths has modified. In the event you locked in a type of traditionally low mounted charges, many planners now say maintaining a budget mortgage whereas your investments hold working can beat draining accounts to kill it. Loads of retirees with the means to repay the home are selecting to not, on their advisor’s recommendation. If that’s you, you’re not behind. You’re present.
4. Not Maxing Out Each Retirement Account
Finance content material talks about “maxing your 401(okay)” prefer it’s the baseline of maturity. Really maxing one takes an earnings most households don’t have, and the guilt hole between the recommendation and actuality retains some folks from contributing in any respect.
What profitable savers truly do is easier. Seize the complete employer match, as a result of that’s an immediate hundred % return. Then nudge the proportion up some extent yearly or with each elevate. Consistency over a long time is what builds the quantity. The max was by no means the project.
3. Beginning to Save “Late”
The compound curiosity charts all begin at 22, and everybody who didn’t will get to really feel like they missed the one practice. That feeling is doing extra injury than the late begin ever did.
A 40-year-old has a long time of incomes and compounding forward, and mid-career cash normally comes with mid-career earnings, which implies catching up is an actual factor folks do. Each planner has watched late starters retire comfortably. One of the best time was years in the past. The second finest time is that this paycheck, and the guilt is the one factor standing between you and it.
2. Not Following a Line-Merchandise Finances
Right here’s a confession from contained in the business. Numerous monetary planners don’t hold detailed budgets themselves. The folks whose job is cash, not monitoring each greenback. Sit with that one.
What they do as a substitute is automate the necessary stuff. Financial savings and investments transfer the day the paycheck lands, payments are on autopay, and no matter’s left is genuinely free to spend. The system wants one trustworthy setup session and about ten minutes a month. If spreadsheet budgeting works for you, nice. In the event you’ve failed at it six instances, you had been by no means damaged. The strategy was.
1. Making Cash Errors at All
Right here’s the one no person expects on the high of the listing. Each single monetary skilled has their very own corridor of disgrace. The funding that went to zero. The home purchased on the peak. The years of pricey lattes earlier than they knew higher, and sure, a few of them nonetheless purchase the latte.
Ask planners what truly ruins folks financially and so they don’t say errors. They are saying avoidance. The one that made a large number, checked out it, and adjusted at all times finally ends up forward of the particular person too ashamed to open the statements. Errors are tuition. Everybody pays it. The one unforgivable transfer is letting the disgrace hold you from trying, as a result of you’ll be able to’t repair a quantity you refuse to see.

Drop the Guilt, Hold the Plan
The sample throughout all 31 is nearly embarrassingly constant. The massive choices matter enormously, the small ones barely matter in any respect, and guilt has by no means as soon as compounded into wealth.
So choose the one you’ve been beating your self up over the longest and formally let it go. Then save this listing for the following time a finance influencer tries handy the guilt again.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/