There’s nothing inherently unsuitable with Ramon S. The investing his personal cash. However his 25.68% stake in Lopez Inc. creates a corporate-governance query that has attracted surprisingly little consideration: the place does Ramon Ang, the impartial personal investor, go away off and Ramon Angthe chairman and chief govt of San Miguel Corp. (SMC), step in?
His private funding is just not essentially a battle of curiosity. However there are sufficient crimson lights to make the longer reply vital.
Ang acquired the stake by way of his wholly owned funding automobile Illumina Funding Holdings Inc. SMC didn’t purchase the shares, and even clarified in an official disclosure to the Philippine Inventory Change (PSE) that Ang had acted in his private capability.
That is a crucial distinction, nevertheless it doesn’t resolve potential conflicts.
Take into account the numbers.
Lopez Inc. owns 54.74% of Lopez Holdings, which owns 60.67% of First Philippine Holdings (FPH). FPH, in flip, owns 67.84% of First Gen Company (First Gen)’s widespread shares. Hint Ang’s 25.68% by way of these possession layers and you will note that he has roughly 5.79% look-through financial publicity to First Gen.
That isn’t a direct holding or voting proper. However Ang now has a personal economic interest in one of many largest energy teams within the Philippines, whereas persevering with to go one other conglomerate that dominates a lot of the identical business.
The Vitality Regulatory Fee (ERC)’s numbers make that overlap tough to brush apart. At end-2024, SMC accounted for six,079.6 megawatts (MW) of attributable put in producing capability, or 22.44% of the nationwide complete — the nation’s largest share. First Gen ranked third with 3,583 MW, or 13.22%.
These aren’t two corporations that will finally collide in the identical line of enterprise. They already inhabit the identical electrical energy market. They might compete for power plantsrenewable-energy tasks, liquefied pure gasoline (LNG) and different gas contracts, electrical energy prospects, financing, and government-awarded vitality alternatives.
That is the place the battle turns into actual. (READ: ERC scrutiny adds a new wrinkle to Ramon Ang’s Lopez, Inc investment)
The numerous what ifs
What if a pretty producing asset is obtainable on the market and First Gen desires it as badly as San Miguel? Suppose they pursue the identical hydropower undertaking or power-supply contract. Think about commercially delicate data obtained from one aspect doubtlessly giving a bonus to the opposite.
Which Ramon Ang would then present up?
Philippine company regulation anticipated this drawback.
Part 30 of the Revised Company Code addresses administrators who purchase private or pecuniary pursuits that battle with their duties.
Part 33 goes additional: when a director, by advantage of his workplace, takes for himself a enterprise alternative that ought to belong to the company and earnings at its expense, he should account for these earnings, except stockholders representing a minimum of two-thirds of excellent capital inventory ratify the act.
The regulation incorporates an particularly related qualification: the corporate-opportunity rule applies even when the director risked his personal funds.
Caveat: this doesn’t imply that Ang breached both provision by shopping for into Lopez Inc.
There isn’t any proof that SMC needed Crème Investment Corp.’s 25.68% stakethat the chance was first supplied to San Miguel, or that Ang diverted an SMC alternative into Illumina. It might be a step too far to name the acquisition itself illegal.
Ang’s Lopez stake carries an implied worth of roughly P11.56 billion primarily based on his P45-billion valuation of Lopez Inc. Piki Lopez has described him not merely as an investor however as a “accomplice” whose experience may assist develop Lopez companies.
Why governance issues
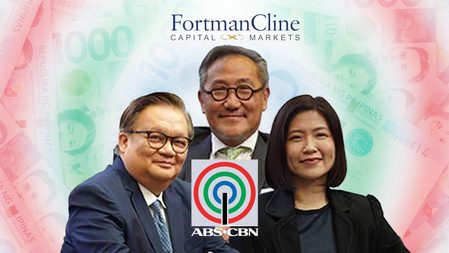
The company relationships are in the meantime changing into extra intertwined. ABS-CBN is raising P6 billion in recent fairness, together with P3.5 billion from I&C Holdings Corp., a newly integrated funding firm fashioned by senior bankers related to Fortman Cline Capital Markets.
Fortman Cline is hardly a stranger to San Miguel. Its printed transaction historical past reveals it suggested SMC on acquisitions that helped remodel the conglomerate into a serious energy and infrastructure participant, together with transactions involving Meralco, Sual, San Roque, Ilijan and, extra not too long ago, the NAIA concession.
None of this establishes that Ang owns, funds or controls I&C. There’s presently no documentary proof that he does. But it surely illustrates how carefully Philippine company circles can intersect — and why governance issues as private investments, advisory relationships and company partnerships overlap.
Does that imply Lopez corporations ought to now keep away from companies the place San Miguel operates?
No.
That may successfully create a non-public non-compete zone round SMC. First Gen shouldn’t abandon a undertaking merely as a result of San Miguel desires it. The governance burden falls principally on Ang and the decision-making course of.
Disclosure and recusal
When pursuits collide, disclosure and recusal change into important. Confidential data can not journey from one aspect to learn one other, and a chance correctly belonging to SMC can’t be redirected towards an enterprise during which Ang has a private monetary curiosity.
The issue may additionally run in reverse. We nonetheless have no idea what governance rights accompany Illumina’s 25.68% Lopez Inc. stake. If Ang or his nominees acquire board seats, veto rights or direct participation in strategic selections, fiduciary obligations may come up on either side.
That’s the reason the following essential disclosure is just not one other proportion.
It’s governance.
And there may be one coincidence value placing on the desk.
On August 3, earlier than I&C emerged publicly, the market was abuzz with speculations that an Ang-led investor group was making ready to inject P3.5 billion into ABS-CBN for a 39% financial curiosity. ABS-CBN subsequently denied that Ang and Manuel V. Pangilinan had been negotiating to take over administration.
Eleven days later, the disclosed transaction includes I&C investing precisely P3.5 billion for what our calculations counsel may change into roughly 38% of enlarged ABS-CBN.
The numbers are remarkably shut.
However coincidence is just not proof. Nothing disclosed to this point establishes that Ang owns, funds or controls I&C. The parallel is nonetheless tough sufficient to disregard — and vital sufficient for buyers to maintain watching.
None of this presumes wrongdoing. Good governance exists exactly as a result of respectable enterprise pursuits generally collide.
The size makes complacency tough. SMC held 22.44% of attributable nationwide put in producing capability at end-2024; First Gen had 13.22%. Between them sits Ramon Ang—SMC chairman and CEO on one aspect and, by way of Illumina, proprietor of 25.68% of the holding firm above the opposite.
These pursuits can coexist.
The take a look at comes when they need the identical factor.
And when that day arrives, the query will now not be whether or not Ramon Ang purchased his Lopez stake along with his personal cash.
Will probably be which Ramon Ang has the fiduciary responsibility to step away.
I welcome your views on these and different points the place selections made in energy form the nation’s financial future.
Beneath are some Vantage Level items you may need missed:
Click on right here for extra Vantage Point articles.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/
https://www.rappler.com/voices/newsletters/vantage-point-companions-power-when-ramon-ang-san-miguel-goes-up-against-lopez-first-gen/