The Ministry of Taxation offers these pointers in Official Discover No. 7403/CT-TMDT on the tax legal responsibility of individuals providing digital data content material services and products and internet affiliate marketing companies in e-commerce.
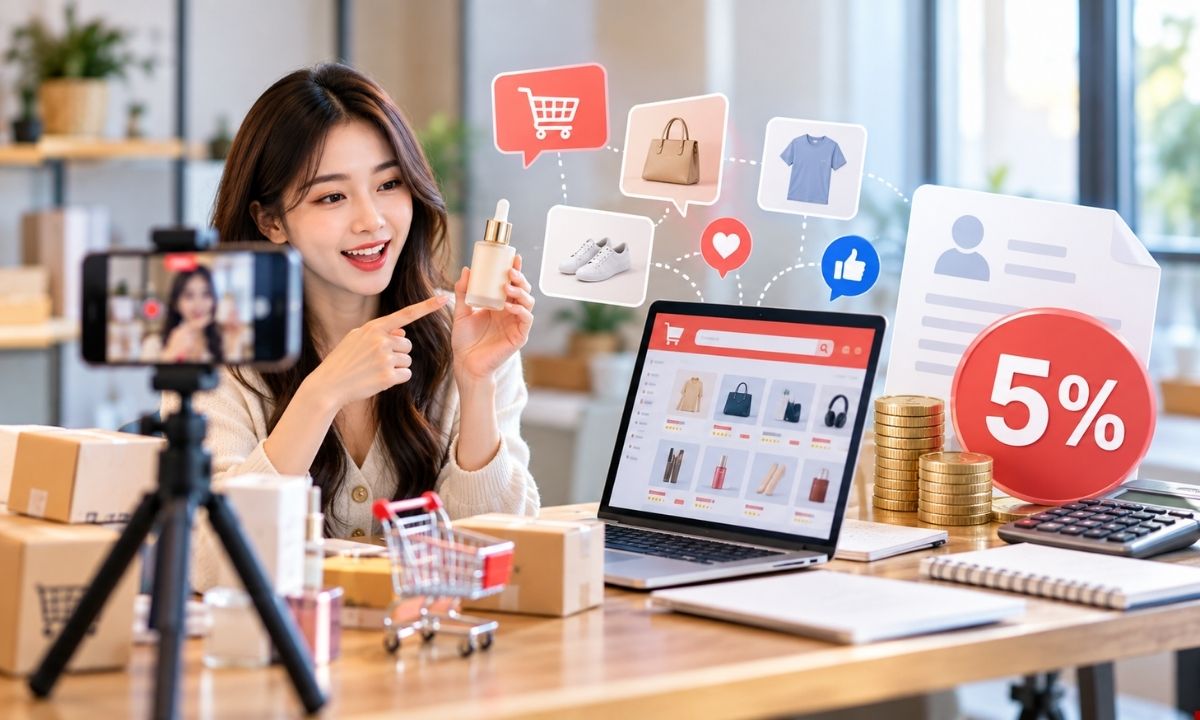
In Official Discover No. 7403/CT-TMDT, the Ministry of Taxation offers steerage on the appliance of a private revenue tax price (PIT) of 5% to internet affiliate marketing actions on e-commerce platforms. This can be a notable provision in Part 1 of the Official Message. Particular:
Relating to the revenue tax price: In line with Part 14, Article 3 of Regulation on E-Commerce No. 122/2025/QH15, internet affiliate marketing companies in e-commerce are the promotion of products and companies by way of entry hyperlinks, referral codes or related strategies linked to an e-commerce platform. Accordingly, internet affiliate marketing actions on e-commerce platforms are topic to the tax price relevant to the availability of services and products with digital data content material associated to leisure, video video games, digital movies, digital photographs, digital music and digital promoting, for which the private revenue tax price is 5% in accordance with level dd, clause 3, article 7 of Regulation on Private Earnings Tax No. 109/2025/QH15.
In line with Official Discover No. 7403/CT-TMDT, tax liabilities are decided based on the kind of revenue earned by a person. If an individual receives revenue beneath an employment contract or collective settlement concluded with an income-paying group or particular person in accordance with labor regulation, such revenue is set as revenue from salaries and remuneration. Organizations and people paying revenue should withhold, declare and pay revenue tax in accordance with the laws.
If a person is concerned in digital content material creation, product promotion or internet affiliate marketing actions on e-commerce platforms or digital platforms and receives revenue from a platform or model apart from salaries or wages in reference to enterprise actions, such revenue is taken into account enterprise revenue. Entrepreneurial households and entrepreneurs should perform tax registration, declaration and cost in accordance with Decree No. 68/2026/ND-CP and Decree No. 141/2026/ND-CP.
Relating to the tax price, the official message states that internet affiliate marketing companies in e-commerce means the promotion of products and companies through entry hyperlinks, referral codes or related strategies in reference to an e-commerce platform.
Accordingly, internet affiliate marketing actions on e-commerce platforms are topic to the tax price relevant to the availability of services and products containing digital data content material within the fields of leisure, video video games, digital movies, digital photographs, digital music and digital promoting. The PIT price relevant to those actions is 5%, in accordance with level dd, clause 3, article 7 of the Earnings Tax Regulation of 2025.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/