Key Factors
- The 2027 restrict for 401(okay), 403(b), 457 and Thrift Financial savings Plan contributions rises $1,000 to $25,500, with catch-up contributions of $8,500 at age 50 and $11,750 at ages 60 to 63.
- IRA contributions keep capped at $7,500 for 2027 with a $1,100 catch-up, however the Roth IRA earnings phase-out climbs to $158,000 to $173,000 for single filers.
- These limits apply to cash you contribute in 2027, so increase your payroll election throughout open enrollment or earlier than your first January paycheck.
The IRS introduced on November 12, 2026 that staff can put as much as $25,500 right into a 401(okay) in 2027, up from $24,500 this 12 months. The identical restrict covers 403(b) plans, authorities 457 plans and the federal Thrift Financial savings Plan.
The IRS announcement leaves the IRA restrict at $7,500, the identical as 2026. You’ll be able to examine each determine with our 401(okay) contribution and earnings limits web page.
The complete tables sit in IRS Discover 2026-66 (PDF File). Complete worker and employer contributions can attain $75,000, and the wage threshold for necessary Roth catch-ups rises to $155,000.
These modifications come per week after the IRS launched the 2027 tax brackets and customary deduction.
.tci-retire27{border:2px strong #141414;border-radius:8px;overflow:hidden;font-family:inherit;colour:#141414;background:#fff;margin:24px 0}.tci-retire27 .tci-retire27-head{background:#141414;colour:#fff;padding:14px 18px;font-weight:700;font-size:18px;line-height:1.3}.tci-retire27 .tci-retire27-head span{colour:#f6c061}.tci-retire27 desk{width:100%;border-collapse:collapse;margin:0;font-size:15px}.tci-retire27 th{background:#f9f7f5;colour:#55504a;text-transform:uppercase;font-size:12px;letter-spacing:.04em;text-align:left;padding:10px 14px;border-bottom:1px strong #e5e0d8}.tci-retire27 td{padding:10px 14px;border-bottom:1px strong #e5e0d8;vertical-align:high}.tci-retire27 tbody tr:nth-child(even) td{background:#fcfbf9}.tci-retire27 td.tci-retire27-label{font-weight:600}.tci-retire27 tbody tr.tci-retire27-total td{background:#f6c061;font-weight:700;border-bottom:none}.tci-retire27 .tci-retire27-foot{background:#f9f7f5;colour:#8a8378;font-size:12px;padding:10px 14px;border-top:1px strong #e5e0d8}@media (max-width:640px){.tci-retire27 thead{show:none}.tci-retire27 desk,.tci-retire27 tbody,.tci-retire27 tr,.tci-retire27 td{show:block;width:100%;box-sizing:border-box}.tci-retire27 tr{border-bottom:1px strong #e5e0d8;padding:8px 0}.tci-retire27 td{border-bottom:none;padding:4px 14px}.tci-retire27 td(data-label):earlier than{content material:attr(data-label);show:block;font-size:11px;font-weight:400;text-transform:uppercase;letter-spacing:.04em;colour:#8a8378}.tci-retire27 tbody tr:nth-child(even) td{background:clear}.tci-retire27 tbody tr.tci-retire27-total{background:#f6c061;border-bottom:none}.tci-retire27 tbody tr.tci-retire27-total td{background:clear}}2027 Retirement Contribution Limits
| Account Or Restrict | 2026 | 2027 |
|---|---|---|
| 401(okay), 403(b), 457 And TSP Worker Restrict | $24,500 | $25,500 |
| Catch-Up Contribution, Age 50 And Older | $8,000 | $8,500 |
| Catch-Up Contribution, Ages 60 To 63 | $11,250 | $11,750 |
| Complete Worker And Employer Contributions | $72,000 | $75,000 |
| Conventional And Roth IRA | $7,500 | $7,500 |
| IRA Catch-Up, Age 50 And Older | $1,100 | $1,100 |
| SIMPLE IRA And SIMPLE 401(okay) | $17,000 | $17,500 |
| SIMPLE Increased Restrict At Sure Small Employers | $18,100 | $19,100 |
| SIMPLE Catch-Up, Age 50 And Older | $4,000 | $4,000 |
| SIMPLE Catch-Up, Ages 60 To 63 | $5,250 | $5,250 |
| SEP IRA | $72,000 | $75,000 |
| HSA, Self-Solely Or Household Protection | $4,400 / $8,750 | $4,500 / $9,000 |
| Roth Catch-Up Wage Threshold | $150,000 | $155,000 |
Supply: IRS. The Faculty Investor.
Save For Later
Would you want to avoid wasting this?
E mail AddressSave This
Web site
What Are The 2027 401(okay) Contribution Limits?
The 2027 worker contribution restrict for 401(okay), 403(b), governmental 457 plans and the TSP is $25,500. Employees 50 and older can add an $8,500 catch-up contribution, for a complete of $34,000. Anybody turning 60, 61, 62 or 63 in 2027 will get a better $11,750 catch-up if the plan gives catch-ups, for a complete of $37,250. The $25,500 restrict is per individual throughout each 401(okay) and 403(b) you contribute to. Governmental 457(b) plans carry their very own separate restrict, as our comparability of 403(b) and 457 plans explains.
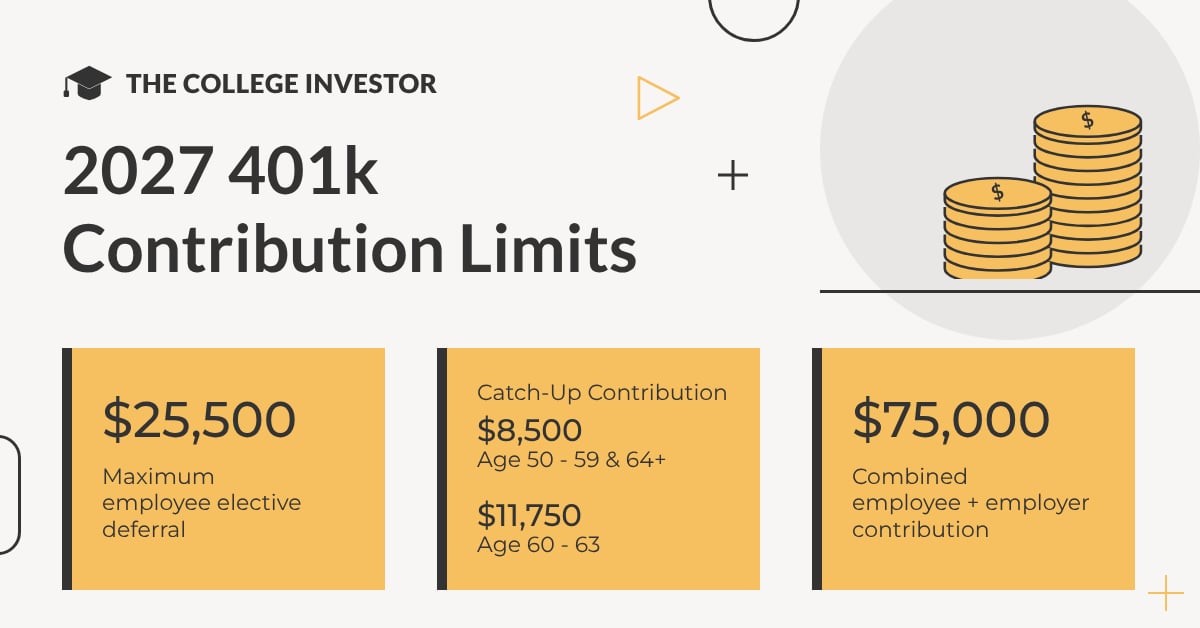
Complete contributions from you and your employer, together with the match and any revenue sharing, can attain $75,000 in 2027, up $3,000. Catch-up contributions sit on high of that cap. The upper ceiling issues most for self-employed savers with a solo 401(okay) and for staff who use after-tax cash for a mega backdoor Roth.
.tci-maxsave27{border:2px strong #141414;border-radius:8px;overflow:hidden;font-family:inherit;colour:#141414;background:#fff;margin:24px 0}.tci-maxsave27 .tci-maxsave27-head{background:#141414;colour:#fff;padding:14px 18px;font-weight:700;font-size:18px;line-height:1.3}.tci-maxsave27 .tci-maxsave27-head span{colour:#f6c061}.tci-maxsave27 desk{width:100%;border-collapse:collapse;margin:0;font-size:15px}.tci-maxsave27 th{background:#f9f7f5;colour:#55504a;text-transform:uppercase;font-size:12px;letter-spacing:.04em;text-align:left;padding:10px 14px;border-bottom:1px strong #e5e0d8}.tci-maxsave27 td{padding:10px 14px;border-bottom:1px strong #e5e0d8;vertical-align:high}.tci-maxsave27 tbody tr:nth-child(even) td{background:#fcfbf9}.tci-maxsave27 td.tci-maxsave27-label{font-weight:600}.tci-maxsave27 tbody tr.tci-maxsave27-total td{background:#f6c061;font-weight:700;border-bottom:none}.tci-maxsave27 .tci-maxsave27-foot{background:#f9f7f5;colour:#8a8378;font-size:12px;padding:10px 14px;border-top:1px strong #e5e0d8}@media (max-width:640px){.tci-maxsave27 thead{show:none}.tci-maxsave27 desk,.tci-maxsave27 tbody,.tci-maxsave27 tr,.tci-maxsave27 td{show:block;width:100%;box-sizing:border-box}.tci-maxsave27 tr{border-bottom:1px strong #e5e0d8;padding:8px 0}.tci-maxsave27 td{border-bottom:none;padding:4px 14px}.tci-maxsave27 td(data-label):earlier than{content material:attr(data-label);show:block;font-size:11px;font-weight:400;text-transform:uppercase;letter-spacing:.04em;colour:#8a8378}.tci-maxsave27 tbody tr:nth-child(even) td{background:clear}.tci-maxsave27 tbody tr.tci-maxsave27-total{background:#f6c061;border-bottom:none}.tci-maxsave27 tbody tr.tci-maxsave27-total td{background:clear}}How A lot You Can Save In 2027
| Age In 2027 | 401(okay) Worker Restrict | IRA Restrict | Mixed |
|---|---|---|---|
| Below 50 | $25,500 | $7,500 | $33,000 |
| 50 To 59, Or 64 And Older | $34,000 | $8,600 | $42,600 |
| 60 To 63 | $37,250 | $8,600 | $45,850 |
Supply: IRS. The Faculty Investor.
Who Should Make Roth Catch-Up Contributions In 2027?
Employees who earned greater than $155,000 in FICA wages from their employer in 2026 should make any 2027 catch-up contributions as Roth contributions. The edge rose from $150,000. That SECURE 2.0 requirement first utilized in 2026, and our protection of the Roth catch-up rule for prime earners explains who it hits.
Roth catch-ups go in after tax, in order that they now not decrease your taxable earnings that 12 months. In case your plan doesn’t provide a Roth choice, staff above the edge can’t make catch-up contributions in any respect. Ask HR now whether or not your plan gives a Roth 401(okay) earlier than you set your 2027 election.
What Are The 2027 IRA Contribution Limits?
The 2027 IRA contribution restrict is $7,500, unchanged from 2026. Savers 50 and older can add $1,100, for $8,600 in complete. The restrict applies throughout your entire conventional and Roth IRAs mixed, as our IRA contribution and earnings limits web page explains.
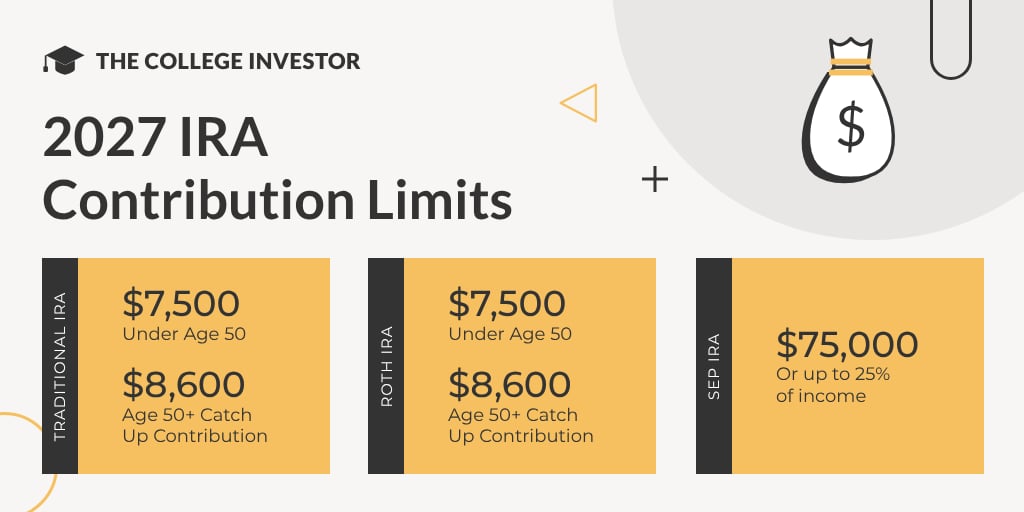
The IRA restrict solely strikes in $500 steps, so it stays flat till inflation pushes it over the subsequent step. A non-working partner can fund a spousal IRA as much as the identical restrict, so long as the couple information collectively and has sufficient earned earnings to cowl each contributions.
2027 Roth IRA And Conventional IRA Revenue Limits
Single filers and heads of family could make a full Roth IRA contribution with modified AGI under $158,000 in 2027, and eligibility ends at $173,000. Married {couples} submitting collectively part out between $250,000 and $260,000. Savers above these ranges can nonetheless use a backdoor Roth IRA.
.tci-iraphase27{border:2px strong #141414;border-radius:8px;overflow:hidden;font-family:inherit;colour:#141414;background:#fff;margin:24px 0}.tci-iraphase27 .tci-iraphase27-head{background:#141414;colour:#fff;padding:14px 18px;font-weight:700;font-size:18px;line-height:1.3}.tci-iraphase27 .tci-iraphase27-head span{colour:#f6c061}.tci-iraphase27 desk{width:100%;border-collapse:collapse;margin:0;font-size:15px}.tci-iraphase27 th{background:#f9f7f5;colour:#55504a;text-transform:uppercase;font-size:12px;letter-spacing:.04em;text-align:left;padding:10px 14px;border-bottom:1px strong #e5e0d8}.tci-iraphase27 td{padding:10px 14px;border-bottom:1px strong #e5e0d8;vertical-align:high}.tci-iraphase27 tbody tr:nth-child(even) td{background:#fcfbf9}.tci-iraphase27 td.tci-iraphase27-label{font-weight:600}.tci-iraphase27 tbody tr.tci-iraphase27-total td{background:#f6c061;font-weight:700;border-bottom:none}.tci-iraphase27 .tci-iraphase27-foot{background:#f9f7f5;colour:#8a8378;font-size:12px;padding:10px 14px;border-top:1px strong #e5e0d8}@media (max-width:640px){.tci-iraphase27 thead{show:none}.tci-iraphase27 desk,.tci-iraphase27 tbody,.tci-iraphase27 tr,.tci-iraphase27 td{show:block;width:100%;box-sizing:border-box}.tci-iraphase27 tr{border-bottom:1px strong #e5e0d8;padding:8px 0}.tci-iraphase27 td{border-bottom:none;padding:4px 14px}.tci-iraphase27 td(data-label):earlier than{content material:attr(data-label);show:block;font-size:11px;font-weight:400;text-transform:uppercase;letter-spacing:.04em;colour:#8a8378}.tci-iraphase27 tbody tr:nth-child(even) td{background:clear}.tci-iraphase27 tbody tr.tci-iraphase27-total{background:#f6c061;border-bottom:none}.tci-iraphase27 tbody tr.tci-iraphase27-total td{background:clear}}2027 IRA Revenue Part-Out Ranges
| Filer | 2026 Vary | 2027 Vary |
|---|---|---|
| Roth IRA: Single Or Head Of Family | $153,000 – $168,000 | $158,000 – $173,000 |
| Roth IRA: Married Submitting Collectively | $242,000 – $252,000 | $250,000 – $260,000 |
| Roth IRA: Married Submitting Individually | $0 – $10,000 | $0 – $10,000 |
| Conventional IRA Deduction: Single, Coated At Work | $81,000 – $91,000 | $83,000 – $93,000 |
| Conventional IRA Deduction: Joint, Contributor Coated | $129,000 – $149,000 | $133,000 – $153,000 |
| Conventional IRA Deduction: Joint, Solely Partner Coated | $242,000 – $252,000 | $250,000 – $260,000 |
| Conventional IRA Deduction: Separate, Coated At Work | $0 – $10,000 | $0 – $10,000 |
Supply: IRS. The Faculty Investor.
The normal IRA deduction phase-out solely applies if you or your partner has a retirement plan at work. A single filer lined at work loses the deduction between $83,000 and $93,000 of modified AGI. Our Roth vs. conventional IRA determination tree helps you choose between the 2.
How Do SIMPLE IRA, SEP IRA And HSA Limits Change In 2027?
The SIMPLE IRA restrict rises to $17,500 from $17,000, and sure small employers can provide a better $19,100 restrict. SIMPLE catch-ups keep at $4,000 for many staff 50 and older and $5,250 at ages 60 to 63. SEP IRA contributions can attain 25% of compensation, capped at $75,000, per our SEP IRA contribution limits web page.
HSA limits for 2027 had been set earlier this 12 months at $4,500 for self-only protection and $9,000 for household protection, as we reported when the 2027 HSA limits got here out. Savers 55 and older can add $1,000. Many savers deal with an HSA as a second retirement account.
What Occurs To The Saver’s Credit score In 2027?
Beginning in 2027, the Saver’s Credit score now not applies to 401(okay) or IRA contributions. The brand new $1,000 Saver’s Match replaces it for these contributions, with the federal match deposited into the saver’s retirement account. A footnote in Discover 2026-66 confirms the Saver’s Credit score survives just for contributions to ABLE accounts.
For ABLE contributions, the credit score’s high earnings restrict rises to $83,000 for married {couples} submitting collectively, $62,250 for heads of family and $41,500 for single filers. Decrease-income savers who contribute to a 401(okay) or IRA ought to look ahead to the match after they file their 2027 return, and we observe it alongside the opposite finest tax breaks households can use.
How Do The 2027 Limits Have an effect on Scholar Mortgage Funds?
Conventional 401(okay) contributions decrease your adjusted gross earnings, and the Compensation Help Plan units your fee from AGI. That makes the brand new $25,500 restrict one of many few authorized methods to chop a RAP scholar mortgage fee with out incomes much less. RAP costs 1% to 10% of complete AGI, primarily based on the $10,000 bracket your earnings lands in.
We ran a single borrower with no dependents and a $90,000 wage by way of the 2027 guidelines, utilizing the usual deduction and no different earnings. With no 401(okay) contributions, the RAP fee is $600 a month. Maxing the 401(okay) at $25,500 drops AGI to $64,500 and the fee to $322.50. Federal earnings tax falls $5,198 underneath the 2027 federal tax brackets.
.tci-rap27{border:2px strong #141414;border-radius:8px;overflow:hidden;font-family:inherit;colour:#141414;background:#fff;margin:24px 0}.tci-rap27 .tci-rap27-head{background:#141414;colour:#fff;padding:14px 18px;font-weight:700;font-size:18px;line-height:1.3}.tci-rap27 .tci-rap27-head span{colour:#f6c061}.tci-rap27 desk{width:100%;border-collapse:collapse;margin:0;font-size:15px}.tci-rap27 th{background:#f9f7f5;colour:#55504a;text-transform:uppercase;font-size:12px;letter-spacing:.04em;text-align:left;padding:10px 14px;border-bottom:1px strong #e5e0d8}.tci-rap27 td{padding:10px 14px;border-bottom:1px strong #e5e0d8;vertical-align:high}.tci-rap27 tbody tr:nth-child(even) td{background:#fcfbf9}.tci-rap27 td.tci-rap27-label{font-weight:600}.tci-rap27 tbody tr.tci-rap27-total td{background:#f6c061;font-weight:700;border-bottom:none}.tci-rap27 .tci-rap27-foot{background:#f9f7f5;colour:#8a8378;font-size:12px;padding:10px 14px;border-top:1px strong #e5e0d8}@media (max-width:640px){.tci-rap27 thead{show:none}.tci-rap27 desk,.tci-rap27 tbody,.tci-rap27 tr,.tci-rap27 td{show:block;width:100%;box-sizing:border-box}.tci-rap27 tr{border-bottom:1px strong #e5e0d8;padding:8px 0}.tci-rap27 td{border-bottom:none;padding:4px 14px}.tci-rap27 td(data-label):earlier than{content material:attr(data-label);show:block;font-size:11px;font-weight:400;text-transform:uppercase;letter-spacing:.04em;colour:#8a8378}.tci-rap27 tbody tr:nth-child(even) td{background:clear}.tci-rap27 tbody tr.tci-rap27-total{background:#f6c061;border-bottom:none}.tci-rap27 tbody tr.tci-rap27-total td{background:clear}}A Maxed 401(okay) And A RAP Fee In 2027
| Single Borrower, $90,000 Wage | No 401(okay) | $25,500 To 401(okay) |
|---|---|---|
| Adjusted Gross Revenue | $90,000 | $64,500 |
| RAP Price | 8% | 6% |
| Month-to-month RAP Fee | $600 | $322.50 |
| Federal Revenue Tax | $10,690 | $5,492 |
| Yearly Financial savings | — | $8,528 |
Supply: IRS. The Faculty Investor.
RAP’s brackets create cliffs price planning round. The identical borrower contributing $9,000 lands at $81,000 of AGI and nonetheless pays 8%, or $540 a month. Contributing $10,000 drops AGI to $80,000 and the speed to 7%, which cuts the fee to $466.67. That further $1,000 saves $880 a 12 months in funds, so take a look at your election in our RAP calculator first.
Your RAP fee is usually primarily based on the AGI out of your most up-to-date federal tax return, so 2027 contributions present up if you recertify utilizing your 2027 return. Debtors whose employers provide a scholar mortgage 401(okay) match may also accumulate retirement matching {dollars} on their scholar mortgage funds.
What Ought to You Do Now?
- Elevate your 401(okay) election for January. Maxing out at $25,500 takes $980.77 per biweekly paycheck, and our order of operations for retirement saving exhibits the place the 401(okay) matches.
- End your 2026 IRA contribution. You’ve till April 15, 2027 to fund a 2026 IRA on the 2026 limits, and our greatest IRA accounts record might help you open one.
- Verify your Roth IRA eligibility. Evaluate your anticipated 2027 modified AGI with the brand new ranges, and discover ways to calculate your adjusted gross earnings for those who aren’t certain.
- Ask about Roth catch-ups for those who earned over $155,000. Your plan wants a Roth 401(okay) choice so that you can hold making catch-up contributions.
- Run the RAP math earlier than open enrollment ends. Our record of pre-tax strikes that decrease your scholar mortgage fee covers the 401(okay), HSA and dependent care FSA collectively.
The submit 2027 401(okay) And IRA Contribution Limits From The IRS appeared first on The Faculty Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/