Cash doesn’t stretch the best way it used to, and it’s not likely a thriller why. Groceries creep up a greenback at a time, insurance coverage renews just a little greater yearly, and subscriptions multiply within the background till a financial institution assertion exhibits up and no person can clarify the place all of it went.
Right here’s the half most individuals by no means cease to consider. Firms value for inertia. They’re relying on you not calling to barter, not evaluating charges, not studying the advantageous print on a renewal discover.
The households paying the least often aren’t the luckiest or the richest. They’re simply those who spend a couple of minutes trying.
This checklist ranks 25 of the best methods households are decreasing their month-to-month prices proper now, loosely ordered by affect and the way lengthy the financial savings stick. Some take two minutes to arrange as soon as and by no means want consideration once more. Others are small shifts in behavior that change how a family spends with out anybody feeling disadvantaged.
Stack a handful of those collectively and the financial savings compound quick, so it’s value studying via to primary, the place the largest mindset shift on this entire checklist is ready.
25. Meal Plan Across the Gross sales Flyer, Not the Recipe
Groceries sit close to the highest of most family budgets. In contrast to a mortgage or a automobile fee, it’s a invoice that renegotiates itself each single week, whether or not a family realizes it or not.
Most households construct meal plans backward. They choose recipes first, then purchase no matter these recipes want at no matter value occurs to be on the shelf.
Flipping the order modifications the maths. Begin with the shop’s weekly flyer or app (most retailers submit digital variations with additional app-only coupons), see which proteins are literally discounted, and construct the week’s dinners round these. Rooster thighs on sale develop into two dinners; a marked-down pork loin turns into dinner plus just a few lunches.
Three habits multiply the financial savings: store as soon as per week with a strict checklist as an alternative of creating frequent “fast journeys” that invite impulse buys, keep away from grocery buying on an empty abdomen, and purchase additional of a staple when it hits an actual low so it may be frozen or shelved, the identical intuition behind understanding which warehouse membership buys are literally value it in bulk and which by no means are. Households who run this method constantly report reducing grocery spend by someplace round 15 to 25 p.c with out consuming any otherwise.

24. Unplug the Vampires
Proper now, a number of gadgets in a typical dwelling are drawing energy whereas doing nothing helpful. It’s known as phantom load, and standby electronics can quietly account for five to 10 p.c of a house’s complete electrical invoice, typically $100 to $200 a yr.
The worst offenders observe a sample: cable and satellite tv for pc containers (a few of the hungriest standby gadgets made), sport consoles left in “prompt on” mode, desktop computer systems left asleep as an alternative of shut down, and wall chargers left plugged in lengthy after the gadget is gone.
Then there’s the traditional ignored offender: an previous second fridge working within the storage to relax just a few cans of soda. An inefficient older fridge working in a sizzling storage can value $100 or extra a yr by itself.
A $15 to $25 sensible energy strip cuts energy to peripherals robotically as soon as the principle gadget shuts off, and it’s a genuinely helpful instance of a sensible gadget that’s really value shopping for as an alternative of a gimmick. Flipping a console out of instant-on mode takes thirty seconds in a settings menu, and if that storage fridge is generally empty, unplugging it is likely one of the best wins on this complete checklist.

23. Decrease the Water Heater to 120°F
Few home equipment quietly eat as a lot of an influence invoice because the water heater. It runs all day preserving a full tank sizzling, whether or not anybody makes use of it or not, and sometimes accounts for 15 to 18 p.c of dwelling power prices.
Most items ship from the manufacturing facility set round 140°F, hotter than any family wants and an actual scald danger for younger youngsters or older adults.
Dialing it again to 120°F is likely one of the quickest modifications on this checklist, typically saving someplace within the vary of 4 to 22 p.c on water heating prices. On most tanks it’s a visual dial close to the underside; on electrical fashions it could sit behind a small panel that pops off with a screwdriver.
Two add-ons whereas standing there: an older tank that also feels heat to the contact can profit from a $20 insulation blanket, which may minimize standby warmth loss by 25 to 45 p.c. And draining just a few gallons from the underside valve annually flushes out sediment that in any other case forces the heater to work more durable and fail years sooner than it ought to.

22. Use the Library Like It’s Nonetheless 1995
The native library quietly grew to become top-of-the-line subscription bundles most individuals already personal and by no means use, a pleasant reminder that not every part value having has quietly was one of many issues that was free and isn’t anymore. If a family spends cash on books, audiobooks, or streaming leases, a library card might be sitting on actual financial savings no person’s cashed in.
Digital library apps join a card to the library’s full catalog of ebooks and audiobooks without charge, with loans that return themselves robotically so there aren’t any late charges. One well-liked audiobook app alone can run $15 a month for a single credit score; the library model is free indefinitely.
A number of library programs additionally supply free movie and documentary streaming with a genuinely present choice, plus language-learning platforms and digital newspaper entry that will in any other case value actual cash.
Past the digital aspect, most programs supply museum and zoo passes, instrument libraries for gear used a couple of times a yr, seed libraries for dwelling gardeners, and free assembly area. A couple of minutes on a library’s web site is likely one of the highest-return looking periods most individuals by no means suppose to have.

21. Weatherstrip Doorways and Home windows Earlier than the Subsequent Season
Add up each small hole round a house’s doorways and home windows and the whole provides up quick. In an older dwelling, mixed air leaks can equal the equal of leaving a window cracked open year-round.
Sealing these gaps plus including primary insulation is estimated to save lots of roughly 15 p.c on heating and cooling prices, and the supplies concerned value lower than a pizza night time.
Discovering the leaks is oddly satisfying. On a breezy day, maintain a lit candle or incense stick close to door frames, window edges, and retailers on exterior partitions. If the flame sparkles or the smoke swirls, air is transferring via. The same old suspects: the hole underneath exterior doorways, window sash edges, attic hatches, and the small holes the place pipes or cables cross via an exterior wall.
The fixes are cheap: $10 peel-and-stick weatherstripping tape for door and window edges, an $8 door sweep for the underside of exterior doorways, caulk for stationary gaps, and $5 foam gasket inserts behind outlet covers on exterior partitions, a leak supply virtually everybody misses. A day of this tends to pay for itself inside the first chilly month.

20. Batch Prepare dinner to Minimize Meals Waste
Meals waste is likely one of the sneakiest funds leaks as a result of it by no means exhibits up as a single cost. It exhibits up as wilted produce within the crisper drawer and leftovers no person eats. Estimates on family meals waste counsel the typical household throws out someplace near a fifth of the groceries it buys.
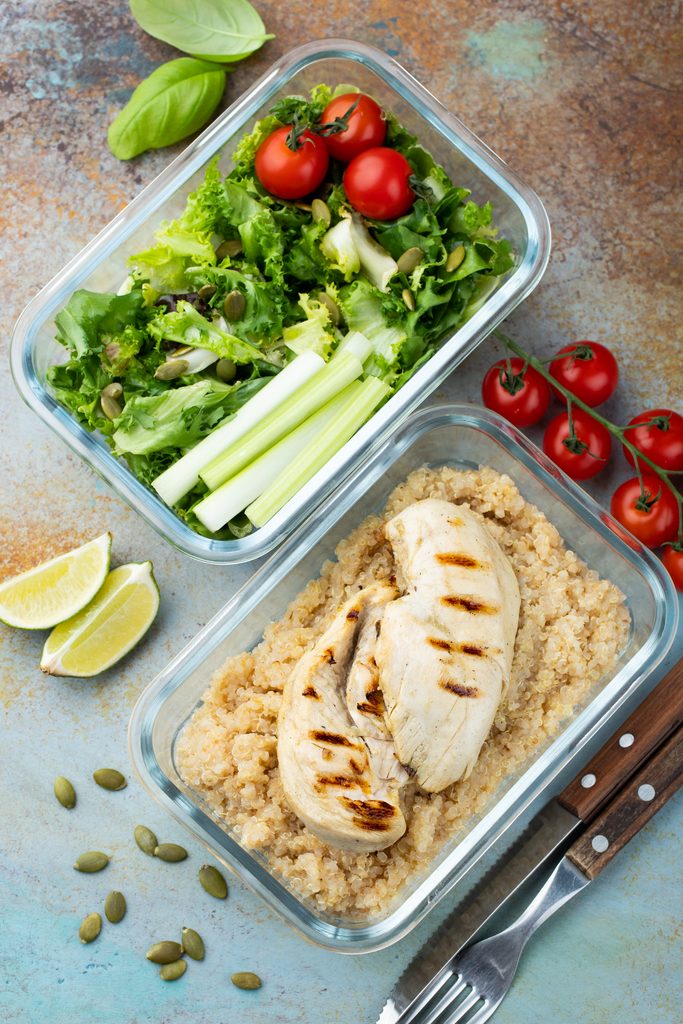
Batch cooking flips that sample. Choose one or two afternoons to cook dinner just a few base proteins and grains in bulk, portion them into the fridge or freezer, and meals come collectively from what’s already ready as an alternative of no matter’s most handy to order, which quietly provides as much as its personal form of takeout tax over the course of a yr.
It additionally makes it far simpler to make use of up produce earlier than it turns, since chopped greens get folded into no matter’s cooking that week fairly than forgotten in a drawer.
One trick that makes it stick: maintain a working checklist on the fridge of something near its expiration date, and deal with that checklist as the start line for the subsequent meal, not an afterthought. Households that undertake this behavior have a tendency to note their grocery invoice and their trash can shrink on the identical time.

19. Swap in Retailer Manufacturers The place It Doesn’t Matter
Retailer-brand merchandise have closed the standard hole on quite a lot of gadgets that used to really feel like a compromise. In lots of classes, the true distinction between a reputation model and the shop’s personal model is nearer to the packaging than the product itself, and pantry staples like flour, sugar, spices, canned greens, and cleansing provides are sometimes made in the identical or comparable services as their branded counterparts.
The trick is being selective fairly than switching every part directly. Objects the place style or texture genuinely issues, like a favourite cereal or a selected condiment, can keep identify model. Staples used principally as an ingredient in one thing else, like canned tomatoes going right into a sauce, are straightforward locations to swap with out anybody noticing.
A easy take a look at works effectively: purchase the store-brand model as soon as, use it in a standard meal, and see if anybody feedback. If no person notices, it turns into a everlasting swap. Throughout a full cart, a dozen small swaps like this will shave 10 to twenty p.c off a grocery invoice.

18. Run Home equipment Throughout Off-Peak Hours
Many utility corporations cost completely different charges relying on the time of day, with electrical energy costing extra throughout peak afternoon and early-evening hours when demand is highest. Households on this sort of plan, or in a deregulated power market, can typically shift a significant share of utilization to cheaper in a single day or early-morning hours with out utilizing much less electrical energy total.
The best targets are home equipment that don’t want an individual watching them. Dishwashers, washing machines, and dryers can all run a delayed cycle set to start out after peak hours finish, and most machines constructed within the final decade have a delay-start button constructed proper into the management panel.
An electrical automobile, if the family has one, is an particularly massive win right here. Charging in a single day as an alternative of proper after work can shift a considerable chunk of family electrical energy use into the cheaper window, typically saving 30 p.c or extra on the price of every cost.
Step one is checking a utility invoice or account portal for time-of-use pricing, since not each supplier affords it and peak home windows range by area.

17. Store Auto Insurance coverage Earlier than Each Renewal
Auto insurance coverage charges have climbed quicker than virtually another common family invoice in recent times, with some areas seeing will increase effectively above 20 p.c in a single yr. The will increase are likely to land hardest on drivers who auto-renew with out evaluating something.
A provider isn’t required to supply its greatest price, solely a price, and it’s relying on most drivers to only pay no matter quantity exhibits up. What surprises lots of people is how otherwise insurers value the very same driver.
The identical individual, identical automobile, and identical driving file can obtain quotes that differ by lots of of {dollars} a yr, as a result of each firm weighs danger components like location, credit-based insurance coverage scores, and driving historical past otherwise.
The one approach to discover the higher quantity is to match, ideally at each renewal fairly than simply when a invoice feels surprising, and it’s precisely the form of comparability sensible customers make a behavior of working earlier than any massive recurring value. Conserving the very same protection ranges whereas buying round means the comparability is solely about value, not about reducing safety.

16. Repair the Leaks No person Can See
Water leaks are sneaky as a result of they hardly ever announce themselves. They often simply present up as a water invoice that’s mysteriously greater than common, and it’s one of many extra literal entries on a working checklist of small leaks that quietly value actual cash over a decade. Water-efficiency estimates counsel the typical family loses near 10,000 gallons a yr to leaks that go fully unnoticed, and roughly one in ten properties has a leak losing 90 or extra gallons a day.
The 2 largest culprits are additionally the most affordable fixes. A working rest room can waste as much as 200 gallons a day, often from a worn flapper valve that prices $2 to $5 and replaces in about ten minutes with no instruments required.
A easy take a look at: drop meals coloring into the tank, wait fifteen minutes with out flushing, and examine whether or not any coloration exhibits up within the bowl. If it does, that’s the leak.
A dripping faucet is offender quantity two. Even one drip per second provides as much as roughly 3,000 gallons a yr. For leaks hiding elsewhere in the home, flip off each fixture and examine whether or not the water meter remains to be transferring, a fast approach to catch an issue in an outside spigot, irrigation line, or water heater earlier than it turns right into a a lot greater restore invoice.

15. Elevate the Deductible, If There’s a Cushion to Cowl It
A deductible features like a dial that most individuals go away set wherever an agent defaulted it years in the past, and that dial instantly controls the month-to-month premium. The extra danger a policyholder agrees to soak up out of pocket, the much less an insurer fees each month.
Transferring an auto deductible from $500 to $1,000 sometimes shaves 10 to twenty p.c off the premium; transferring it greater saves extra. The identical logic applies to dwelling insurance coverage.
The maths works due to how insurance coverage really will get used. Most households file a declare hardly ever, perhaps as soon as each a number of years, however pay the premium each single month no matter whether or not they ever use it, which is precisely the form of trade-off monetary advisors say individuals shouldn’t really feel responsible about making as soon as the numbers help it.
The one sincere prerequisite is an emergency fund that would genuinely take up the upper deductible with out going onto a bank card. If a shock $500 or $1,000 expense must be financed at a excessive rate of interest, it makes extra sense to maintain the decrease deductible for now and revisit this transfer as soon as there’s extra of a cushion.
14. Examine Renters Insurance coverage Even Although It’s Low-cost
Renters insurance coverage is likely one of the least costly insurance policies most individuals will ever purchase, typically $12 to $20 a month to cowl hearth, theft, water harm, and legal responsibility. As a result of it’s so low cost, virtually no person bothers to buy it.
That’s precisely how renters find yourself quietly paying double for similar protection, actually because a coverage obtained added via a landlord’s portal years in the past and by no means obtained revisited, a small however cussed instance of the form of “regular” expense that quietly drains a checking account with out anybody noticing.
A fast comparability at renewal time can minimize an already small invoice in half, which makes it one of many best wins on this checklist although the greenback quantity is modest.
For renters with none coverage in any respect, it’s value remembering {that a} landlord’s insurance coverage covers the constructing, not a tenant’s belongings. One burst pipe in an upstairs unit is sufficient to destroy furnishings, electronics, and clothes, and and not using a private coverage, none of it will get changed.
13. Put Credit score Card Rewards to Work As an alternative of Ignoring Them
A number of households carry a rewards bank card and use it precisely like a debit card, swiping for on a regular basis purchases and letting the factors or money again pile up with out ever redeeming them. Left unused lengthy sufficient, some rewards applications let factors expire or lose worth fully.
The behavior value constructing is redeeming rewards on a set schedule, whether or not that’s money again utilized on to a press release, factors transformed for journey, or a present card towards one thing already being purchased, a behavior that quietly strains up with a few of the different quiet indicators of being higher with cash than most individuals give themselves credit score for.
Pairing a card’s bonus classes, like groceries or fuel, with precise spending in these classes can meaningfully improve the return (typically 2 to five p.c again as an alternative of 1 p.c) with out altering any shopping for habits in any respect.
The one non-negotiable rule is paying the steadiness in full each month. Rewards value just a few p.c again imply nothing subsequent to an rate of interest within the twenties, so this solely works as a real bonus on cash that was already being spent, by no means as a cause to spend extra.
12. Do a Fast DIY-vs-Rent Audit
Loads of family spending goes towards paying another person for a activity that’s genuinely easy to study, whereas different duties get tried as a DIY venture when hiring knowledgeable would really get monetary savings and stop a pricey mistake. The trick is understanding which is which, since loads of neighborhood providers are genuinely value paying somebody for and many aren’t.
Most households by no means sit down and kind their recurring bills into both column. A helpful train: checklist the final a number of service calls or employed duties from the previous yr, then price every one actually. Did it require actual experience, or may it have been dealt with with a video tutorial and an hour of time?
Primary duties like unclogging a drain, changing a rest room flapper, patching drywall, or servicing a lawnmower are likely to land firmly within the DIY column for most individuals, and a single prevented service name can simply save $75 to $150.
On the flip aspect, something involving electrical work, fuel strains, or structural modifications is often value paying for no matter how assured a video makes it look, since a mistake there can value way over the unique service name would have.
11. Perceive What Time period Life Insurance coverage Really Prices
Ask individuals to guess the price of a life insurance coverage coverage and most overestimate considerably, typically by three or 4 occasions the true quantity, in keeping with trade surveys on the subject. That single false impression is a significant cause so many households who genuinely want protection go with out it, and it’s precisely the form of matter that belongs on an inventory of cash conversations each couple ought to have, nonetheless awkward it feels to deliver up.
Time period life insurance coverage tends to be cheap for anybody in fairly good well being, particularly when locked in younger. A wholesome grownup of their 30s can typically discover a 20-year, $500,000 time period coverage for someplace round the price of a few streaming subscriptions a month.
The coverage is easy by design: a protection quantity and a time period size get chosen to cowl the riskiest years, sometimes whereas youngsters are nonetheless at dwelling or a mortgage remains to be excellent. If one thing occurs throughout that time period, the payout goes to the household, tax-free.
Two particulars matter earlier than buying. Charges lock in on the age and well being standing an individual has once they apply, so ready is the one assured approach to pay extra later. And employer-provided life insurance coverage, often just one or two occasions wage, disappears the second somebody modifications jobs, so counting on it alone can go away an actual hole.
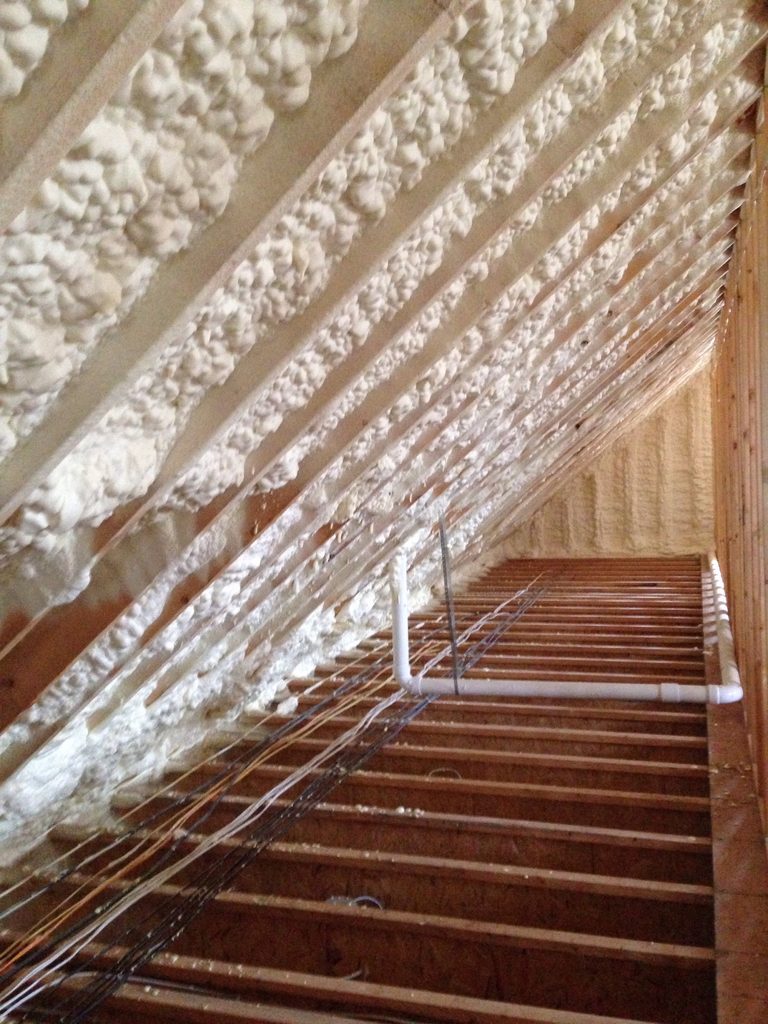
10. Take the Roof and Attic Significantly
Most householders take into consideration their roof precisely twice: as soon as once they purchase the home, and once more the primary time it leaks. However an getting older roof can quietly value cash lengthy earlier than the primary drip exhibits up, because it features because the lid on a house’s complete power system.
Worn shingles, degraded underlayment, and poor attic air flow let heated air escape all winter and let summer season warmth pour in, forcing the HVAC system to run more durable year-round simply to maintain up.
Trendy roofing supplies are likely to mirror extra warmth and seal significantly higher than supplies that have been commonplace fifteen or extra years in the past, and there’s an insurance coverage angle too. Some insurers supply higher charges on newer roofs and are more and more reluctant to resume insurance policies on very previous ones.
Even and not using a full substitute, a easy attic inspection, checking insulation depth and confirming vents aren’t blocked, can reveal whether or not a $200 to $400 improve alone would meaningfully minimize power prices.
9. Test for Errors on a Credit score Report
A credit score rating quietly multiplies or shrinks quite a lot of different payments, because it units the rate of interest on each mortgage and bank card an individual will ever maintain, and in lots of states it even components into insurance coverage premiums. A mediocre rating versus a very good one, on the very same revenue and the very same home, can imply tens of hundreds of {dollars} in additional curiosity over the lifetime of a mortgage.
Right here’s the uncomfortable half. Research on credit score reporting accuracy have discovered that roughly one in 5 stories accommodates some form of error, and some of these errors, like a fee wrongly marked late or an account that isn’t even the buyer’s, can actively drag a rating down.
Most individuals solely uncover this on the worst attainable second: mid-application, when a price comes again greater than anticipated. Checking a credit score report is free via federally mandated annual entry and doesn’t have an effect on the rating in any respect.
Errors, as soon as formally disputed, are required by regulation to be investigated inside 30 days, and a profitable dispute can transfer a rating in a significant approach, typically simply from getting one incorrect line eliminated.
8. Perceive the Actual Vary of Dwelling Fairness Choices
For householders whose internet value seems to be stable on paper however whose month-to-month money circulation feels tight, there’s typically extra flexibility out there than most notice. Dwelling values have risen in quite a lot of markets over the previous a number of years, and that fairness doesn’t have to take a seat untouched, although it’s value understanding the total menu earlier than selecting a path.
A conventional dwelling fairness mortgage or line of credit score provides a brand new month-to-month fee however often comes with a decrease rate of interest than unsecured debt, because the dwelling backs the mortgage.
A cash-out refinance replaces the prevailing mortgage fully. It may make sense when present charges are favorable, nevertheless it’s a much bigger structural change than the opposite choices.
A more moderen choice, a house fairness funding, trades a share of future appreciation for a lump sum at present with no month-to-month fee, which may enchantment to somebody who particularly doesn’t need a new invoice however does surrender a portion of the house’s future worth in change.
None of those is robotically the appropriate one, and every carries actual tradeoffs value understanding absolutely. A house owner contemplating any of them is often higher served getting a number of quotes and studying the advantageous print intently than accepting the primary supply.
7. Finances for Pet Emergencies Earlier than They Occur
Ask a veterinarian in regards to the hardest a part of the job and a standard reply is “financial euthanasia,” the time period for when a treatable emergency comes with a price ticket a household merely can’t cowl. A swallowed toy, a torn ligament, or a sudden sickness can simply run $3,000 to $8,000 in emergency surgical procedure prices, arriving with zero warning.
There are two foremost methods households deal with this danger. One is a devoted pet emergency financial savings fund, constructed progressively the identical approach a automobile restore fund is likely to be, so a invoice within the hundreds doesn’t drive a disaster determination.
The opposite is pet insurance coverage, which spreads the price throughout smaller month-to-month premiums (typically beginning round $20 to $40 a month) in change for protection on the catastrophic situation. Pricing works quite a bit like life insurance coverage: premiums are lowest whereas a pet is younger and wholesome, and something identified earlier than enrollment sometimes counts as pre-existing and received’t be lined.
Neither method is universally higher, and the appropriate one is dependent upon a family’s financial savings habits and danger tolerance. What issues most is choosing one earlier than an emergency forces the choice underneath stress.
6. Be taught the Fundamentals of Paying Down Debt Quicker
Excessive-interest debt, particularly bank cards sitting within the 20-percent-plus vary, has a math downside baked into it. A big share of each minimal fee evaporates into curiosity earlier than it ever touches the precise steadiness, which is a giant a part of why a reasonable bank card steadiness can take years, typically many years, to clear on minimums alone.
Two well-known methods have a tendency to come back up each time this matter will get mentioned. The debt avalanche methodology pays additional towards whichever steadiness carries the best rate of interest first, which saves probably the most cash mathematically over time.
The debt snowball methodology as an alternative pays additional towards the smallest steadiness first, clearing particular person money owed quicker and constructing motivation via seen progress, even when it prices barely extra in complete curiosity.
For households juggling a number of high-interest balances directly, consolidating right into a single fixed-rate mortgage can even simplify the image, changing a number of due dates and charges with one predictable fee. Whichever methodology will get chosen, the households that succeed are those who cease including new fees to the playing cards whereas paying down the previous ones.
5. Name and Ask for a Higher Fee, Particularly on Web
Web and cable suppliers are likely to run on a easy, well-worn playbook: appeal to new clients with a promotional price, then quietly let it climb yearly afterward and hope no person notices. Two neighbors on similar service can find yourself paying wildly completely different month-to-month payments, and the distinction often comes all the way down to who really known as.
The method that tends to work is easy. Calling and mentioning a plan to cancel sometimes routes the decision to a retention division, and that’s the purpose. Retention representatives typically have entry to reductions and promotional pricing that a normal customer support line merely can’t apply, which is basically the identical intuition behind loads of cheapskate-sounding methods that quietly save actual cash as soon as somebody really tries them.
Mentioning a competitor’s marketed value for comparable velocity helps, after which it’s value pausing and letting the consultant work via their choices fairly than filling the silence.
A couple of small issues make the decision land higher: staying well mannered, since representatives have a tendency to assist individuals they like; having the present invoice pulled up earlier than dialing; and understanding the overall competitor panorama even with none actual intention of switching. If the primary supply feels weak, asking instantly whether or not that’s the perfect out there price typically reveals a second tier of reductions that weren’t provided up entrance.
This identical method tends to work simply as effectively on a cellular phone invoice, and a single ten-minute name routinely knocks $15 to $30 a month off an web invoice. It’s value repeating roughly annually, proper round when a promotional price is because of expire.
4. Audit Each Subscription, Not Simply the Apparent Ones
Subscription creep is likely to be the quietest leak in a contemporary family funds. Nothing feels costly at eight or ten {dollars} a month till all of them get added up collectively, and laying all of it out the best way a full yr of “it’s solely $9.99” fees really provides up tends to make the whole genuinely uncomfortable. A number of surveys on the subject have discovered that folks constantly underestimate their complete subscription spending by greater than $100 a month, with the typical family paying for not less than 4 providers it has genuinely forgotten it has.
The repair takes about twenty minutes. Pull up the final two months of financial institution and bank card statements and checklist each recurring cost: streaming platforms, apps, cloud storage, meal kits, health apps, and that free trial from months in the past that quietly transformed to a paid plan.
From there, one easy rule works effectively: something that hasn’t really been used previously thirty days will get canceled.
A couple of spots individuals constantly miss are value calling out. App-store subscriptions hardly ever appear like a standard cost and should be checked instantly in cellphone settings. Annual renewals solely present up annually and are straightforward to neglect fully. Overlapping streaming providers throughout relations can silently double up on the very same content material, typically including $40 to $60 a month with no person capable of say what’s really on greater than a few the platforms being paid for.
One method that works effectively right here is rotating: subscribe to at least one service, watch via what’s needed, cancel, then transfer to the subsequent. The exhibits will nonetheless be there when it’s time to come back again.
3. Set the Thermostat Again on a Schedule
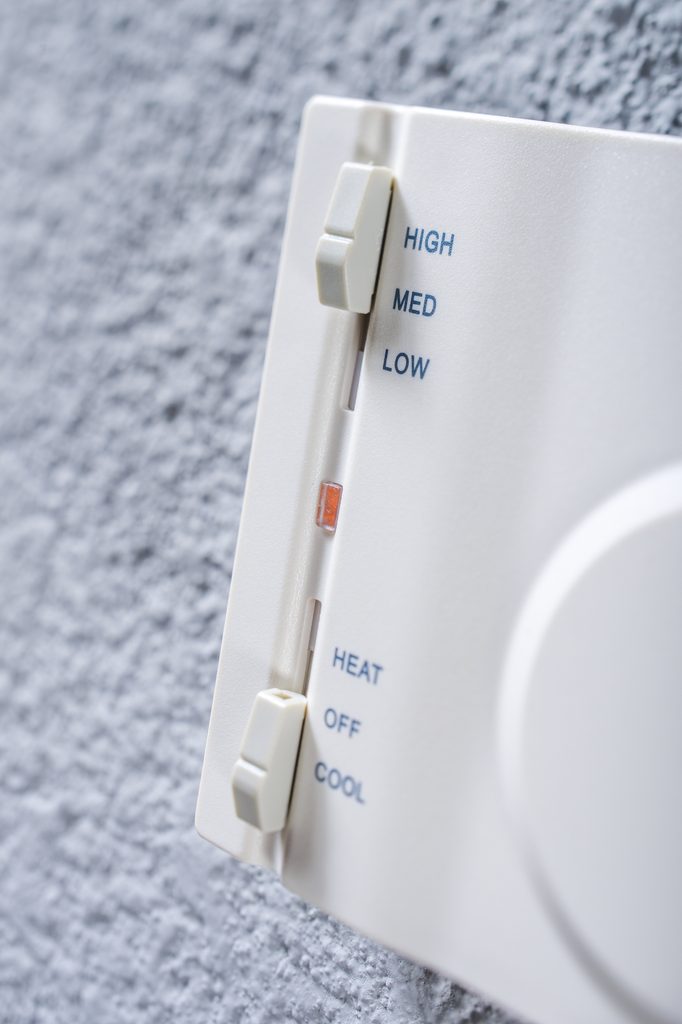
Heating and cooling is, for many households, the one largest line merchandise on the power invoice, sometimes accounting for 40 to 50 p.c of complete power spend. Most properties nonetheless run the HVAC system at full energy for hours daily when no person’s really dwelling or everybody’s asleep and doesn’t want it working that onerous.
The repair prices virtually nothing and takes about two minutes to arrange. Setting the thermostat again by roughly 7 to 10 levels for the hours a family is often away at work, and once more in a single day, is estimated by power researchers to save lots of as much as round 10 p.c a yr on heating and cooling prices, typically $100 to $200 yearly for a one-time adjustment.
A primary programmable thermostat runs about $25. Many utility corporations supply rebates on sensible thermostat fashions that may deliver a $150-plus gadget all the way down to a fraction of that value, with the additional benefit of the thermostat studying a family’s schedule robotically.
Two extra free wins value doing on the identical time: maintain vents away from furnishings so air can really flow into, and swap the HVAC filter each two to a few months, since a clogged filter forces the entire system to work more durable and run longer for the very same outcome. It’s a small, virtually boring behavior, nevertheless it’s precisely the form of change that retains paying each month with out anybody having to consider it once more.
2. Put an Annual “Invoice Day” on the Calendar
Each single tactic on this checklist shares one widespread enemy: drift. A family negotiates the web invoice, switches an insurance coverage coverage, cancels a stack of subscriptions, after which eighteen months cross. Promotional charges expire, premiums creep again up, and a handful of latest subscriptions quietly reappear.
Firms construct their complete pricing mannequin across the assumption that most individuals will set one thing up as soon as and by no means have a look at it once more.
The repair is refusing to depend on reminiscence or willpower and as an alternative placing the entire evaluate on the calendar as a single recurring occasion. Choose a day that’s straightforward to recollect, the primary Saturday of January is a pure anchor and pairs effectively with the opposite cash strikes value making in the beginning of the yr, or the weekend closest to a birthday, and sit down with the latest assertion from each recurring invoice.
That single session covers re-shopping dwelling and auto insurance coverage, making the web retention name once more, reviewing the cellular phone plan and streaming lineup, and, in states with a deregulated power market, evaluating the default electrical energy or fuel price in opposition to the perfect presently out there supply.
Making the session painless issues greater than it sounds. Maintain a easy working notice itemizing every invoice, the present quantity, and the date it was final reviewed, turning the method into filling in blanks fairly than ranging from scratch. For a typical family, a single two- to three-hour session like this tends to be value $500 to $1,500 in discovered financial savings, a greater hourly return than most individuals’s precise jobs, and it’s the one behavior on this complete checklist that retains each different win from quietly evaporating over time.
1. Be taught to Deal with Your self Smarter, Not By no means
Right here’s the uncomfortable fact about why most family budgets finally fail: they get constructed like crash diets. Each nice expense will get minimize directly, the family white-knuckles it for just a few weeks, after which the entire plan collapses in a single annoyed splurge that undoes many of the progress that had been made.
The budgets that really survive long-term don’t remove pleasure fully. They only discover a smarter, cheaper approach to maintain it.
A small, particular luxurious is an efficient instance of how this works in observe. As an alternative of eliminating each discretionary buy, a family can construct a small, devoted “enjoyable fund” into the month-to-month funds, a modest, fastened quantity ($20 to $50 is widespread) put aside particularly for one thing gratifying and nonessential, whether or not that’s a pleasant espresso, tallied actually the best way a full yr of six-dollar espresso habits provides up, a streaming rental, or a small passion buy.
As a result of the quantity is fastened and deliberate for upfront, there’s no guilt connected to spending it. And since it’s genuinely small, it by no means threatens the remainder of the funds the best way an unplanned splurge does.
The identical logic applies to rotating small luxuries as an alternative of committing to all of them completely. A full bottle of a favourite perfume, a premium subscription, or a specialty grocery merchandise doesn’t must be an all-or-nothing determination locked in for a full yr. Making an attempt a smaller measurement, a trial interval, or a rotating subscription mannequin lets a family get pleasure from selection with out the sunk value of a purchase order deserted on a shelf just a few months later.
That’s actually the theme working via this complete checklist. None of that is about residing smaller or reducing out every part gratifying. It’s about refusing to overpay for the very same life a family already has, one invoice, one behavior, and one smarter selection at a time.
Stack even a 3rd of the concepts above, and most households discover they’ve successfully given themselves a increase and not using a single change to their revenue.
Maintain Studying
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/