Key Factors
- Graduate PLUS loans will now not be obtainable to new debtors beginning July 1, 2026.
- Mother and father and graduate college students will face new federal borrowing caps which will go away bigger funding gaps.
- The Compensation Help Plan (RAP) will substitute at present’s income-driven choices for future loans, whereas the SAVE plan is ending.
Federal scholar loans are a important part in how households pay for faculty.
Starting in 2026, new legal guidelines will change how a lot college students and fogeys can borrow and the way these scholar loans are repaid. The modifications are vital, particularly for graduate college students, skilled packages, and households that depend on Mum or dad PLUS loans to shut faculty funding gaps.
Scholar mortgage compensation additionally faces one of many largest shifts in historical past.
For households planning for faculty or graduate college, or these already in compensation on scholar loans, the following yr might be one other wild one with updates and modifications.
Would you want to save lots of this?
We’ll e-mail this text to you, so you may come again to it later!
1. Grad PLUS Loans Are Ending
For years, Graduate PLUS loans have allowed graduate {and professional} college students to borrow as much as the total value of attendance, protecting tuition, charges, housing, and residing bills after different support is utilized.
That possibility ends for brand spanking new debtors after July 1, 2026.
What’s altering
Graduate PLUS loans will now not be issued to college students who take out their first federal mortgage for graduate college on or after that date. College students who have already got Grad PLUS loans for his or her program of examine could also be allowed to proceed borrowing beneath present limits for as much as three years, however new college students to graduate packages won’t have entry.
Why it’s occurring
The One Large Lovely Invoice Act ended the Grad PLUS mortgage program, as lawmakers have expressed concern about limitless borrowing. Graduate college students, whereas being a decrease variety of debtors, have a considerably increased common stability.
Ending Grad PLUS borrowing locations a tough restrict on how a lot graduate college students can finance by way of federal scholar loans.
The way it impacts you
College students coming into legislation college, medical college, MBA packages, and different high-cost graduate packages could now not be capable to borrow sufficient by way of federal loans alone to cowl whole prices.
That shortfall could must be stuffed by way of:
- Scholarships or fellowships
- Employer tuition advantages
- Private financial savings
- Personal scholar loans
What to plan now
Potential graduate college students ought to assessment the total value of packages they’re contemplating and evaluate it to the brand new federal scholar mortgage limits.
2. Mum or dad PLUS Loans Will Have New Limits
Mum or dad PLUS loans have lengthy been the backstop of school financing, permitting mother and father to borrow as much as the total value of attendance for his or her little one’s training.
That, too, is altering.
What’s altering
New Mum or dad PLUS loans issued after July 1, 2026 might be capped at:
- $20,000 per yr per scholar
- $65,000 whole per scholar
Beforehand, mother and father may borrow all the quantity of the price of attendance, minus different monetary support obtained.
Why it’s occurring
Mum or dad PLUS borrowing has grown steadily, and policymakers have expressed concern about mother and father taking up giant balances near retirement, generally with restricted skill to repay.
The brand new caps have been handed as a part of the One Large Lovely Invoice Act, which additionally modified the compensation possibility for future mother or father PLUS loans as properly.
The way it impacts households
Households that rely closely on Mum or dad PLUS loans to afford non-public schools, out-of-state public universities, or high-cost packages could face significant funding gaps.
The change could affect:
- Faculty choice choices
- Whether or not college students dwell on or off campus
- How prices are cut up between mother and father and college students
What to plan now
Mother and father of middle- and high-school college students ought to revisit faculty financial savings plans and anticipated borrowing methods. Households could have to:
- Improve financial savings the place doable
- Examine in-state and lower-cost choices extra rigorously
- Ask schools about institutional grants and tuition fee plans
- Run The Faculty Investor’s How A lot Scholar Mortgage Debt Can I Afford Calculator
Mother and father with present PLUS loans must also monitor consolidation and compensation timelines, as entry to income-based compensation choices depend upon when loans are consolidated.
3. New Borrowing Limits For Graduate And Skilled College students
With the tip of Grad PLUS loans comes a brand new construction of mortgage caps for graduate {and professional} training.
There’ll now be new borrowing limits for each graduate college {and professional} college packages – the primary time the federal government has ever made the excellence in borrowing limits per program.
What’s altering
Federal Direct Unsubsidized Loans will stay obtainable, however with stricter limits:
- $20,500 per yr and $100,000 lifetime for graduate packages
- $50,000 per yr and $200,000 lifetime for skilled packages
Why it’s occurring
This variation is designed to switch open-ended borrowing with strict limits, just like how undergraduate loans function.
The way it impacts college students
Graduate college students in lower-cost packages might even see little distinction. These in costly skilled tracks might have to search out tens of 1000’s of {dollars} elsewhere.
Packages with excessive tuition however modest post-graduation earnings could change into tougher to justify financially beneath the brand new guidelines. Personal lenders can also NOT substitute federal scholar loans for some levels.
What to plan now
Candidates ought to evaluate anticipated debt to reasonable earnings outcomes of their subject. Graduate college choices will must be extraordinarily Return on Funding (ROI) centered.
4. The Compensation Help Plan (RAP) Launches
Borrowing guidelines are solely half the story. Compensation plans are altering too.
What’s altering
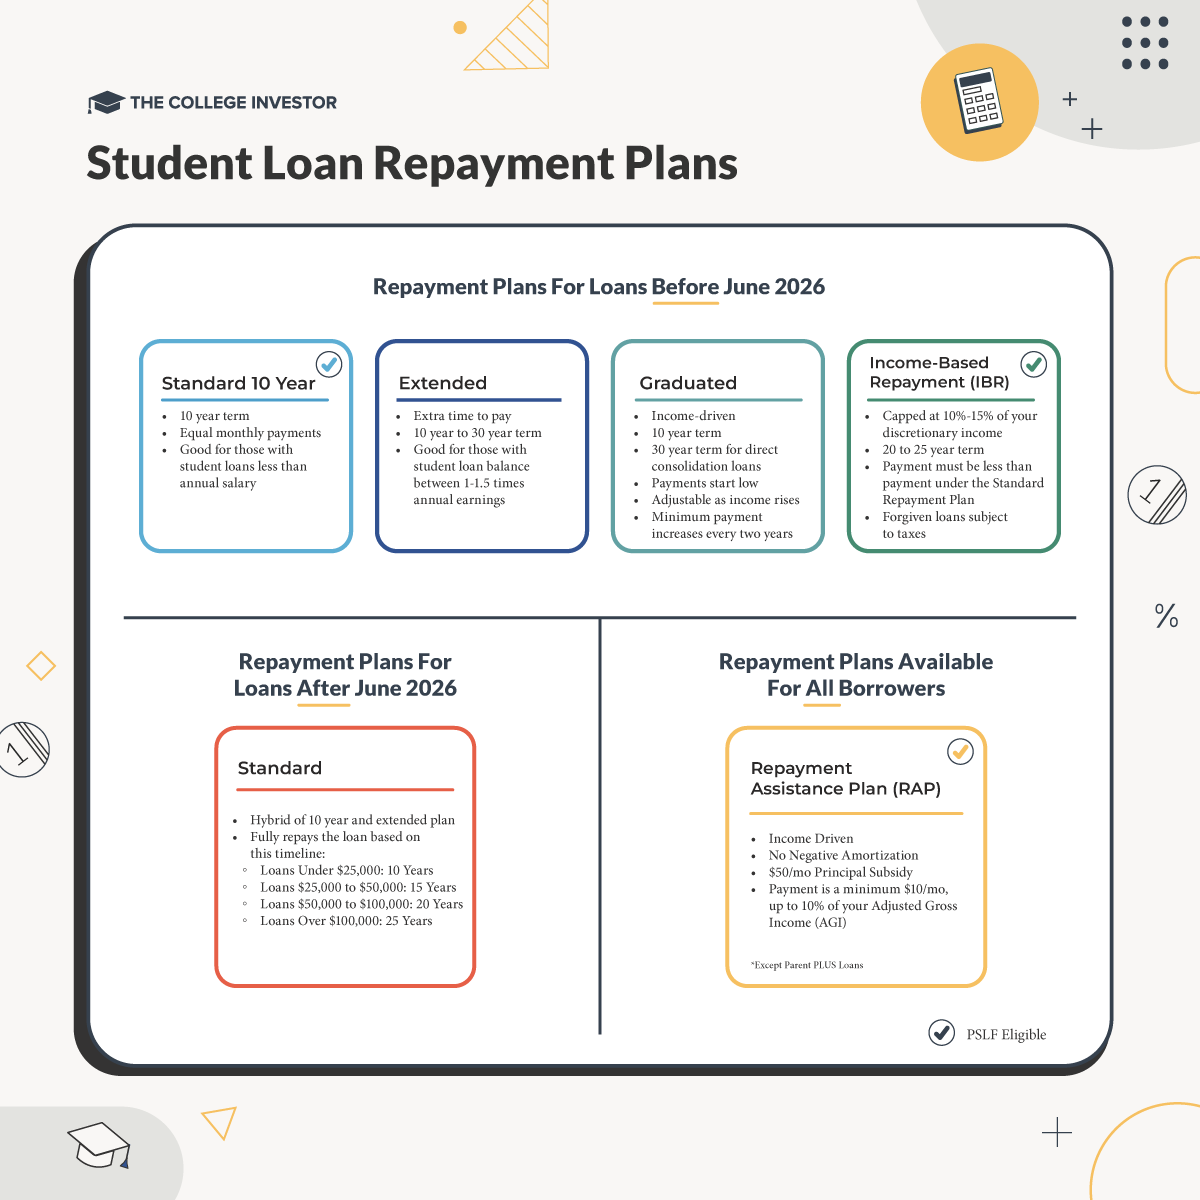
For loans disbursed on or after July 1, 2026, most present income-driven compensation plans might be changed by a brand new Compensation Help Planor RAP.
Debtors will usually select between:
- A regular mounted compensation plan
- The brand new RAP possibility
It is vital to notice that debtors with new Mum or dad PLUS loans after July 1, 2026 will solely have entry to the usual plan.
Why it’s occurring
The federal compensation system has grown complicated, with a number of income-driven plans overlapping. RAP is meant to simplify compensation — although not essentially make it cheaper.
The way it impacts debtors
Funds beneath RAP might be tied to earnings, however forgiveness timelines are longer than beneath current plans. Month-to-month funds for some debtors could rise over time, significantly as earnings will increase.
RAP is compelling, although, as a result of it provides curiosity subsidies and principal discount help.
What to plan now
College students who anticipate to depend on income-driven compensation ought to pay shut consideration to when their loans are disbursed. Loans disbursed earlier than June 30, 2026 will nonetheless keep entry to Revenue Primarily based Compensation (IBR).
5. The SAVE Plan Is Ending
The Saving on a Useful Schooling, or SAVE plan, was a Biden-era initiative that has left over 7 million debtors in limbo. Whereas the courtroom system and OBBBA each have killed the SAVE Plan, the ultimate SAVE Timelines are nonetheless unsure.
What is for certain is that debtors within the SAVE plan must be making choices and planning to vary compensation plans this yr.
What’s altering
SAVE is closed to new debtors and people within the SAVE plan have to resolve on both IBR at present, or anticipate RAP in July. It is doable the Division of Schooling will pressure debtors into a brand new plan on their very own timeline – which will not be useful for these ready in limbo.
Why it’s occurring
SAVE was created beneath earlier govt authority and has confronted authorized and legislative challenges. This was challenged in courtroom, and likewise eradicated by legislation.
The way it impacts debtors
Debtors presently on SAVE ought to run their numbers utilizing The Faculty Investor’s RAP Calculator or Scholar Mortgage Calculator to find out:
- Potential fee beneath IBR
- Potential fee beneath RAP
- Potential commonplace plan fee
Primarily based on these numbers, debtors can resolve which compensation plan would work greatest for them. Debtors pursuing Public Service Mortgage Forgiveness ought to seemingly change sooner, moderately than later, to proceed making ahead progress.
What to plan now
Debtors ought to login to their mortgage servicer and guarantee their contact data is up to date. This can guarantee they do not miss any vital timelines or deadlines.
What Debtors And Households Can Do Now
Crucial step is early planning. The foundations that apply to your loans will rely closely on whenever you borrowand what sort of scholar mortgage you might have.
Households need to:
- Evaluate faculty and graduate college timelines rigorously
- Examine whole program prices in opposition to new mortgage limits
- Improve financial savings or search scholarships earlier
- Ask monetary support workplaces how funding packages could change
Current debtors have to run the numbers on their compensation plans and perceive the modifications.
The federal scholar mortgage system in 2026 might be extra restricted, extra structured, and fewer forgiving for future debtors. Households who perceive these shifts now might be higher positioned to keep away from surprises later and to make training choices that align with long-term monetary stability.
Do not Miss These Different Tales:
@media (min-width: 300px){(data-css=”tve-u-19b7be059ea”).tcb-post-list #post-22108 (data-css=”tve-u-19b7be059f1″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2023/08/What_Are_Private_Non-Profit_Student_Loan_Providers_1280x720-150×150.jpeg”) !vital;}}
10 Finest Personal Scholar Mortgage Lenders For Faculty
10 Finest Personal Scholar Mortgage Lenders For Faculty@media (min-width: 300px){(data-css=”tve-u-19b7be059ea”).tcb-post-list #post-18246 (data-css=”tve-u-19b7be059f1″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2021/05/Credible_Student_Loans_Review_1280x720-150×150.png”) !vital;}}
5 Authorized Methods To Decrease Your Scholar Mortgage Cost
5 Authorized Methods To Decrease Your Scholar Mortgage Cost@media (min-width: 300px){(data-css=”tve-u-19b7be059ea”).tcb-post-list #post-47635 (data-css=”tve-u-19b7be059f1″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2024/10/10_Biggest_FAFSA_Mistakes_1280x720-150×150.png”) !vital;}}
10 Largest FAFSA Errors That Might Price You Monetary Assist
10 Largest FAFSA Errors That Might Price You Monetary Assist
Editor: Colin Graves
The publish 5 Main Scholar Mortgage Adjustments Coming in 2026 appeared first on The Faculty Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/