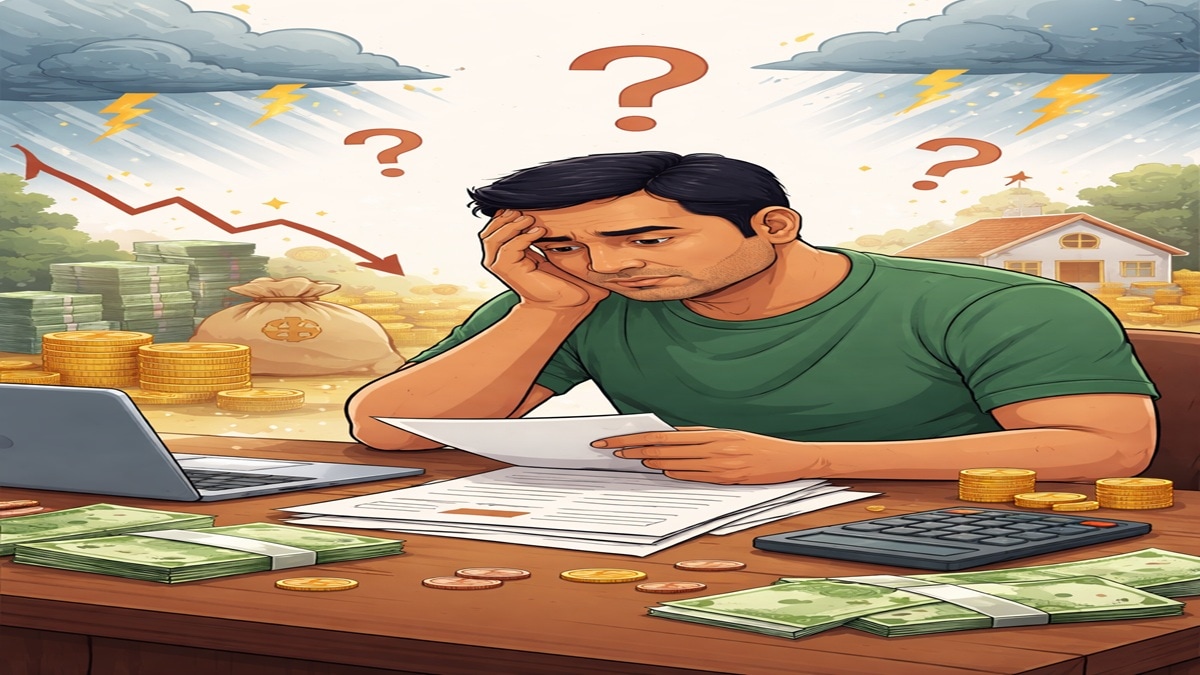
A 43-year-old consumer on international on-line discussion board Reddit lately shared that he has “lastly hit FIRE (kinda FAT)” after years of working overseas and shifting again to India. The funding and monetary particulars he disclosed pertain to his private state of affairs, as posted publicly on the platform.
His numbers look stable.
He has one baby in eighth grade, no debt, and a web value of roughly $1.33 million (round Rs 11 crore). Of this, about $430,000 is parked in retirement accounts that he’s “not planning to the touch anytime quickly”. The remaining $905,000 varieties his energetic, post-tax investable corpus.
His month-to-month bills stand at roughly Rs 2.6 lakh, with housing alone costing Rs 1.4 lakh in a metro metropolis. Based mostly on his calculations, passive revenue generates about Rs 2.7 lakh monthly.
The monetary dashboard snapshot reads: “You’re Coated!”
Passive: Rs 2.7 lakh
Bills: Rs 2.6 lakh
Surplus: +Rs12K
FIRE Mode: On.
“On paper, I’m there. However psychologically it feels form of fragile?” he wrote.
That single line has sparked a wider dialogue in India’s rising FIRE (Monetary Independence, Retire Early) group: Is passive revenue equal to bills actually sufficient? Or ought to there be an even bigger security buffer?
Is matching revenue and expense sufficient?
For somebody in India with over Rs 2.5 lakh month-to-month bills and passive revenue nearly masking it, the margin seems mathematically acceptable. However what occurs if markets underperform for five–7 years?
Mohit Basant Bagdi, Founding Member & Head of Funding Analysis at MIRA Cash, says that is the place the chance begins.
“Having passive revenue equal to your month-to-month bills might look excellent in an Excel sheet, however actual life is way extra unpredictable. Inflation alone steadily erodes buying energy — Rs 1 lakh a month as we speak will really feel meaningfully smaller 5–7 years from now. In case your revenue and bills are precisely matched, your FIRE plan turns into extraordinarily fragile.”
In India, city inflation typically runs larger than headline CPI. College charges, healthcare, hire, journey and way of life prices can simply rise 6–8% yearly. At Rs 2.6 lakh monthly as we speak, bills may cross Rs 3.5 lakh in 5 years if inflation averages 7%.
That skinny Rs 12,000 surplus might not keep comfy for lengthy.
Bagdi cautions additional: “There may be additionally the chance of one-off however high-impact occasions: medical emergencies, household obligations, taxation adjustments or perhaps a extended market downturn. In case your passive revenue leaves no surplus, any sudden shock forces you both again into dependence or into liquidating property on the worst doable time.”
Making ready for five–7 years of weak markets
One of many Reddit consumer’s greatest issues was: “What if markets underperform for five–7 years?”
This is called sequence-of-return threat — when early retirement coincides with weak market returns and common withdrawals amplify losses.
Bagdi explains that the answer lies in construction, not prediction.
“Making ready for weak markets is much less about forecasting downturns and extra about structuring your corpus intelligently. The simplest instrument is a multi-bucket technique that aligns investments with when the cash can be wanted.”
He suggests:
- Preserve 3–4 years of bills in low-risk debt funds for speedy withdrawals.
- Maintain the subsequent 5–7 years of bills in a mixture of short-duration debt and hybrid funds.
- Lengthy-term investments of 7-10 years or extra needs to be made in hybrid and fairness funds the place progress can compound.
“This association assures that you simply by no means need to promote shares in a foul market to cowl your residing bills. You spend from safer buckets whereas giving progress property time to get better. Counting on a single funding pool is likely one of the quickest methods to break a FIRE plan, particularly within the first decade when sequence-of-return threat is at its peak.”
For somebody with roughly Rs 7–8 crore actively invested and annual bills of about Rs 32 lakh, such a construction can defend the plan throughout volatility.
FIRE will not be about survival
One other query raised is whether or not passive revenue equal to bills is enough in any respect.
Bagdi is evident: “FIRE will not be about barely surviving. It’s about long-term flexibility, room for error, and peace of thoughts throughout a long time. That requires a major buffer — each by way of surplus passive revenue and a larger-than-basic retirement corpus — to maintain by an extended lifespan and life’s uncertainties.”
In Indian situations, many advisors suggest aiming for a withdrawal charge nearer to three–3.5% moderately than 4%, given larger inflation and healthcare prices.
A bigger buffer additionally turns into vital when a baby’s larger schooling is just a few years away. Personal faculty schooling in India can price Rs 25–40 lakh, whereas abroad schooling can run into crores.
If such objectives should not ring-fenced individually, retirement corpus might face stress.
Why FIRE typically feels insecure
Maybe essentially the most relatable a part of the Reddit submit was not the numbers — however the emotion.
“On paper, I’m there. However psychologically it feels form of fragile?”
Bagdi says this sense is frequent.
“This can be very frequent to really feel financially insecure even after attaining FIRE on paper. The first cause is that spreadsheets can’t seize real-life uncertainty. Markets don’t transfer in straight strains, inflation isn’t secure, tax guidelines evolve, and life brings sudden prices — particularly health-related or family-driven bills.”
He provides: “A 3–4% withdrawal charge might look protected mathematically, however emotionally it feels very totally different whenever you now not have a wage and your web value swings 10–20% in a single market 12 months. That anxiousness will not be irrational — it’s a human response to giving up energetic revenue whereas nonetheless dealing with long-term monetary commitments.”
“Insecurity normally signifies that the FIRE plan lacks satisfactory buffers, optionality, or sources of non-market-linked revenue. Reaching FIRE is a monetary milestone, however feeling safe is a psychological journey. As spending patterns stabilise, markets revert to long-term traits, and people see their plan working in actual time, that insecurity typically reduces. So sure, feeling unsure initially is totally regular.”
Summing up…
The Reddit consumer’s numbers counsel he has achieved monetary independence by standard requirements. No debt. Corpus that covers bills. Retirement funds untouched.
However the dialogue highlights an vital distinction: Monetary independence is a mathematical milestone. Monetary consolation is a buffer.
For anybody in India with Rs 2.5 lakh or extra in month-to-month bills, merely matching passive revenue to bills will not be sufficient. A well-structured bucket technique, conservative withdrawal charge, inflation planning and a significant surplus are important to show FIRE from a spreadsheet victory into long-term peace of thoughts. As a result of generally, even when the app says “You’re Coated!”, emotional safety takes just a little longer to reach.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/