Key Factors
- SAVE debtors report their 90-day and ultimate 30-day deadlines passing with no plan change, and the Scholar Mortgage Servicing Alliance says nobody has been manually moved off SAVE but.
- The Schooling Division’s settlement with Missouri commits it to shifting each SAVE borrower, and federal regulation ends SAVE by July 1, 2028, so a sluggish rollout nonetheless ends in a brand new plan.
- Nobody will get a shock invoice: servicers should ship the brand new fee quantity a minimum of 21 days earlier than the primary fee is due.
SAVE plan debtors are watching their 90-day deadlines go with nothing taking place. Many acquired a 90-day discover, then a ultimate 30-day discover, and their accounts nonetheless present the forbearance with no fee due.
The Scholar Mortgage Servicing Alliance advised Cash this week that no borrower has been manually moved off SAVE. The Schooling Division says greater than 2 million debtors have picked a brand new plan, and Cash estimates about 5.5 million are nonetheless weighing whether or not to depart SAVE or keep.
Many holdouts now consider the SAVE plan deadlines had been a bluff. We learn it in another way: sluggish motion isn’t the identical as no motion, and each SAVE borrower will nonetheless land in a brand new plan within the coming months. Our SAVE exit timeline tracks the place every wave of notices stands.
Save For Later
Would you want to save lots of this?
E mail AddressSave This
Web site
What Are SAVE Debtors Reporting After Their Deadlines Handed?
Most SAVE debtors report that nothing modified. A Nelnet borrower whose 90-day discover and 30-day extension had each run out posted in r/StudentLoans that the account nonetheless confirmed SAVE, the SAVE Plan Pause Forbearance and a November 2028 due date. The warning banner urging a plan selection had disappeared, and no electronic mail or letter adopted.
An Edfinancial borrower every week previous the ultimate deadline shared a brand new electronic mail titled “You Have a Restricted Time to Choose a New Reimbursement Plan.” It repeats that debtors who don’t apply will go to the Customary Reimbursement Plan, or the Tiered Customary Plan for scholar loans coming into compensation on or after July 1, 2026, but it surely units no new date.
Commenters with Nelnet and Aidvantage described related notices, and lots of stated they’ll keep put till they’re moved.
Why Gradual Motion Doesn’t Imply SAVE Debtors Received’t Be Moved
SAVE debtors can be moved as a result of the Schooling Division is certain to do it by regulation. Below the settlement settlement, the Division agreed to maneuver all SAVE debtors into different compensation plans. The One Huge Stunning Invoice Act additionally ends SAVE, PAYE and ICR by July 1, 2028 it doesn’t matter what occurs in courtroom.
In accordance with Scott Buchanan, govt director of the Scholar Mortgage Servicing Alliance, the idea that the Division can’t transfer debtors has “zero veracity.” He advised Cash the actual bottleneck is telephone and electronic mail assist as soon as greater payments arrive, which is why servicers have despatched exit notices in waves since July 1 as an alternative of .
We’ve seen this sample earlier than. In 2025, SAVE debtors sat in limbo with no introduced timeline, and curiosity nonetheless restarted on schedule on August 1, 2025, although debtors reported ready weeks in some instances for it to replicate on their accounts.
The open query now could be timing: a brand new submitting this week within the Havens lawsuit pressed the Division for a schedule, and Newsweek stories the timeline stays unsettled.
What Does Ready In SAVE Forbearance Price?
Ready prices curiosity and forgiveness credit score. Curiosity has accrued on SAVE balances since August 1, 2025, and SAVE forbearance months don’t depend straight towards Public Service Mortgage Forgiveness or income-driven compensation forgiveness. PSLF debtors should purchase these months again, however the buyback queue runs over two years.
Take a single borrower with $35,000 in federal scholar loans at 6.5% and $55,000 of adjusted gross revenue, the identical borrower we used to check RAP and Customary funds. Curiosity provides about $190 a month, or roughly $2,900 since August 2025, with nothing counted towards forgiveness.
Decrease-income debtors have even much less motive to attend. Earnings-Based mostly Reimbursement can nonetheless produce a $0 fee for debtors incomes below 150% of the federal poverty line, and hundreds of thousands leaving SAVE may nonetheless owe $0 whereas these months depend towards forgiveness.
That is very true for debtors which can be dealing with unemployment, which is a remark we’ve heard rather a lot these days. In case you’ve just lately misplaced your job, it’s the very best time to use for IBR as a result of you’ll be able to lock in a $0 fee for the subsequent 12 months.
Will SAVE Debtors Get A Shock Scholar Mortgage Invoice?
One factor many debtors are involved about is getting a shock invoice as a result of communication has been missing by way of a lot of this course of. Debtors are anxious that they really could have already been enrolled in compensation and simply not acquired a billing assertion.
We don’t see that occuring.
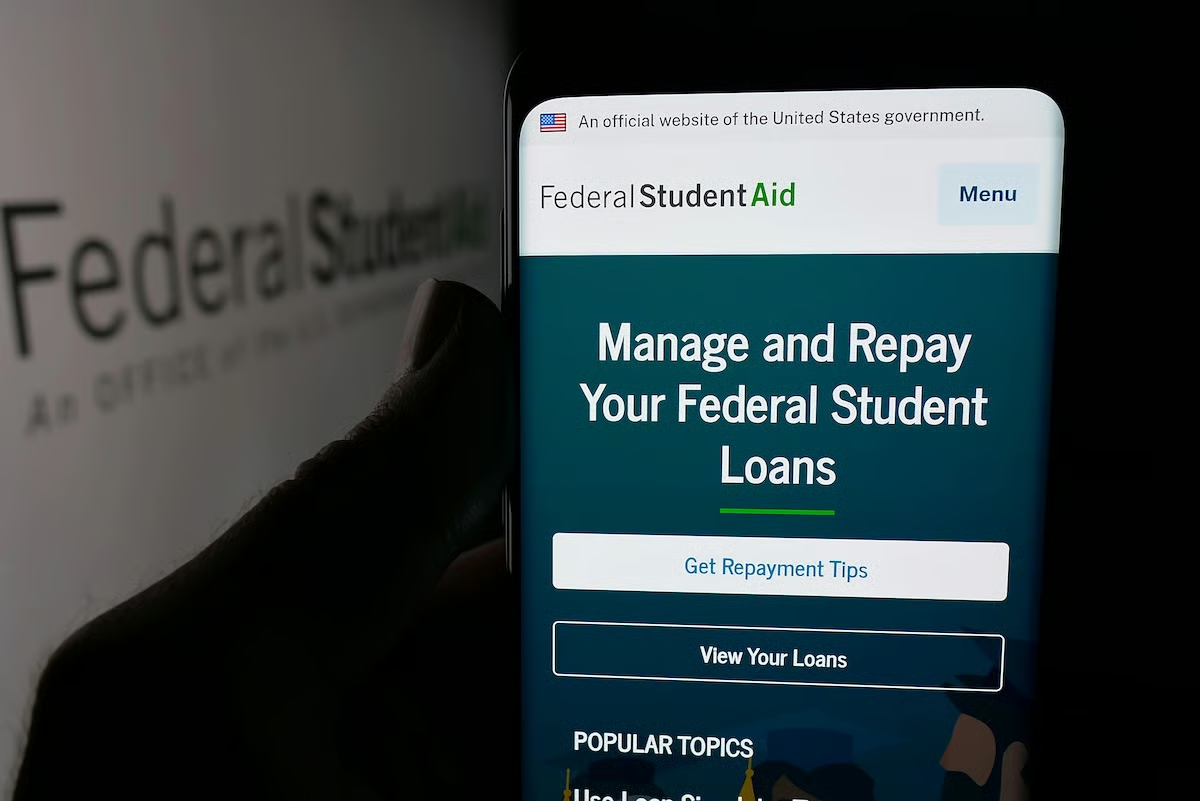
When a servicer strikes a SAVE borrower to the Customary or Tiered Customary Plan, StudentAid.gov says the servicer will ship the brand new month-to-month fee quantity a minimum of 21 days earlier than the primary due date. That matches the overall federal rule {that a} fee is due no earlier than 21 days after the billing assertion goes out. You may estimate that quantity at this time with our scholar mortgage calculator.
Debtors on autopay will see the withdrawal rise to the brand new quantity mechanically in the event that they already had autopay setup, the Division notes. Three weeks can be a brief window for those who haven’t been planning for compensation over the previous few months.
Ignoring the primary invoice carries actual prices. Federal scholar loans are reported delinquent to the credit score bureaus at 90 days and go into default at 270 days.
What Ought to SAVE Debtors Do Now?
- Affirm your standing. Verify StudentAid.gov and your servicer’s website, and search your inbox for the ultimate discover topic traces so you realize the place you stand.
- Run your numbers. Evaluate RAP, IBR and Customary in our scholar mortgage fee calculator earlier than your servicer chooses for you.
- Select the cheaper plan for PSLF. Public service staff ought to choose whichever plan prices much less, and our RAP vs. IBR comparability reveals the place that crossover sits.
- Ask about forbearance for those who can’t pay. Debtors can request a brand new forbearance as soon as they enroll in a brand new compensation plan. You can not do it beforehand.
Continuously Requested Questions
Can I Nonetheless Decide A Plan After My SAVE Deadline Handed?
Sure. SAVE debtors can apply for RAP, IBR or one other eligible plan after the deadline, and debtors positioned on Customary can nonetheless swap later. Our SAVE exit timeline tracks every step.
Why Does My Account Say My Fee Is Due In 2028?
From a database standpoint, they might not go away a clean enddate, and in order that was entered as a placeholder. It’s not a promise that funds keep paused till 2028. Your servicer will transfer you earlier than then and ship your new fee a minimum of 21 days forward, as our ultimate discover protection explains.
Editor: Colin Graves
The submit SAVE Plan Deadline Handed? Why You’ll Nonetheless Be Moved appeared first on The School Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/