State-chartered nonprofit scholar mortgage authorities are rolling out graduate college loans to catch debtors who lose entry to federal Grad PLUS loans on July 1.
Why it issues: The One Large Stunning Invoice Act closes Grad PLUS to new debtors and imposes onerous caps on what graduate {and professional} college students can borrow from the federal authorities.
For college students in costly medical, dental, legislation, and different superior applications, that leaves a funding hole that solely non-public loans or institutional support can fill — and a handful of states are actually attempting to fill it themselves.
Driving the information: Connecticut and Minnesota have every launched their very own state-backed graduate mortgage applications aimed squarely on the Grad PLUS hole. Different states, like Rhode Island, have supplied a graduate mortgage for years.
In Connecticut, the Connecticut Increased Training Supplemental Mortgage Authority (CHESLA) launched the MyCHESLA Grad Mortgage. It provides mounted charges beginning at 5.50%, reimbursement phrases of 5, 10, or 15 years, and in-school cost selections that embody interest-only, full deferment, or fast principal-and-interest funds.
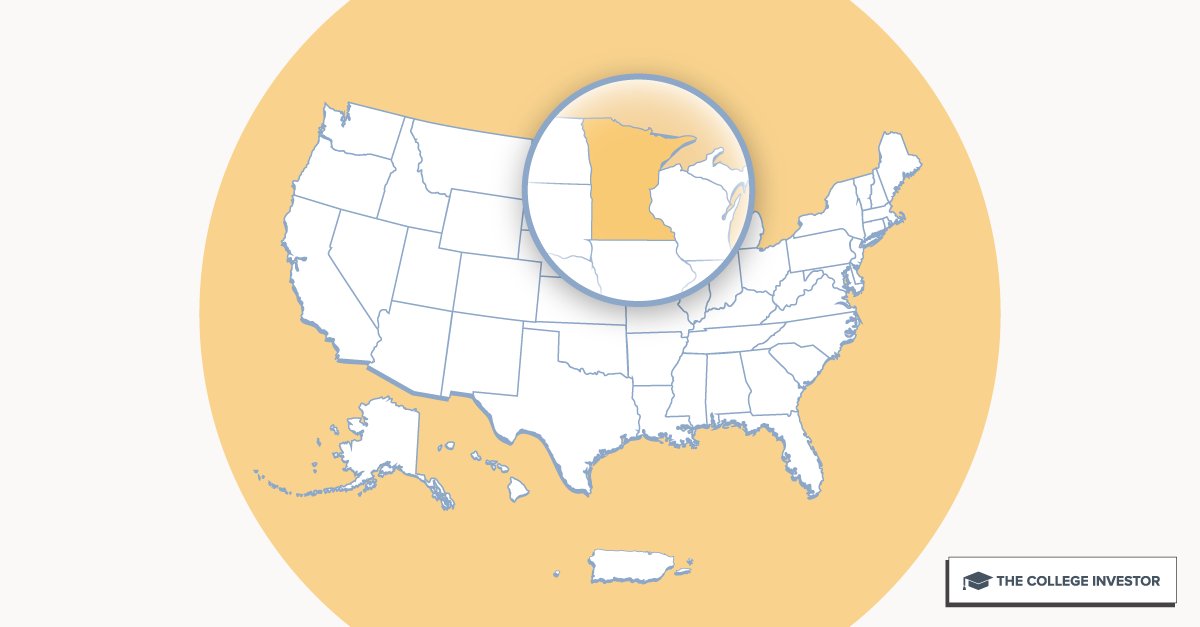
Minnesota adopted with the SELF Grad Mortgage by way of its Workplace of Increased Training. This system units mounted charges primarily based on whether or not a borrower has a co-signer and which time period they select (10, 15, or 20 years) moderately than on a credit score rating. As of this week, 35 Minnesota faculties and universities had signed on.
Rhode Island (RISLA) has supplied a graduate mortgage for a number of years, providing borrowing choices to these pursuing an MBA, medical college, legislation college, and extra.
The federal backdrop: Beginning July 1, 2026, new graduate debtors are capped at $20,500 a 12 months and $100,000 whole.
Skilled college students (future medical doctors, dentists, and legal professionals) can borrow $50,000 a 12 months and $200,000 whole.
The larger image: Connecticut and Minnesota are usually not the one choices. A number of state nonprofit lenders already make graduate loans out there, together with the Rhode Island Scholar Mortgage Authority (RISLA), which lends nationwide to grasp’s and doctoral college students, and Texas-based Brazos, which provides graduate borrowing for Texas residents.
These lenders sometimes pitch decrease charges and fewer charges than for-profit non-public lenders, and a few carry borrower-protection options federal loans are shedding. State-based non-profit lenders are distinctive in that they will sometimes entry funds at decrease price attributable to their standing as a state-affiliated group. They’re then capable of go these decrease prices onto debtors.
How this connects: The Faculty Investor has tracked the Grad PLUS phase-out carefully, together with affirmation that graduate borrowing now sits contained in the $257,500 lifetime cap and warnings that the brand new limits might push some higher-cost applications and faculties to shut.
With federal support shrinking, state nonprofit authorities are rising as one of many few lower-cost options — although availability nonetheless relies upon closely on the place a borrower lives or research.
It is also at all times necessary to check conventional graduate non-public loans to state non-profits. Your particular person state of affairs should earn you a greater charge privately.
What’s subsequent: Count on extra states with non-profit lenders to create related applications within the coming 12 months. Debtors ought to examine any state nonprofit possibility in opposition to non-public lenders on charge, charges, time period size, and in-school reimbursement flexibility earlier than signing.
Do not Miss These Different Tales:
@media (min-width: 300px){(data-css=”tve-u-19ee10757af”).tcb-post-list #post-43514 (data-css=”tve-u-19ee10757b5″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2023/08/TheCollegeInvestor_AllSizes_Best_Dental_School_Student_Loans_02_1280x720-150×150.jpeg”) !necessary;}}
5 Finest Dental College Scholar Loans: Federal And Non-public
5 Finest Dental College Scholar Loans: Federal And Non-public@media (min-width: 300px){(data-css=”tve-u-19ee10757af”).tcb-post-list #post-22108 (data-css=”tve-u-19ee10757b5″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2023/08/What_Are_Private_Non-Profit_Student_Loan_Providers_1280x720-150×150.jpeg”) !necessary;}}
10 Finest Non-public Scholar Mortgage Lenders For Faculty
10 Finest Non-public Scholar Mortgage Lenders For Faculty@media (min-width: 300px){(data-css=”tve-u-19ee10757af”).tcb-post-list #post-18246 (data-css=”tve-u-19ee10757b5″){background-image: url(“https://thecollegeinvestor.com/wp-content/uploads/2021/05/Credible_Student_Loans_Review_1280x720-150×150.png”) !necessary;}}
5 Authorized Methods To Decrease Your Scholar Mortgage Cost
5 Authorized Methods To Decrease Your Scholar Mortgage Cost
Editor: Colin Graves
The publish State Nonprofit Lenders Step In As Grad PLUS Loans Disappear July 1 appeared first on The Faculty Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/