Picture supply: Getty Photographs
State Pension considerations are rising — and for a lot of, it is probably not sufficient for a snug retirement.
With markets unstable and the price of dwelling nonetheless excessive, counting on a single earnings in later life seems to be more and more dangerous. The State Pension offers a basis, nevertheless it was by no means meant to do the heavy lifting.
The true danger? Ready too lengthy to behave.
So what can buyers do now to take management of their future earnings? For me, it begins with placing cash to work constantly — particularly throughout unstable intervals when long-term alternatives start to emerge.
Volatility is alternative
The chart under exhibits how a constant £500 a month invested over 20 years may translate into very totally different ranges of retirement earnings, relying on long-term market returns.
A 4% annual return interprets into round £9,700 a yr of second earnings. At 8%, this rises to just about £15,000. And at 10%, it climbs to round £18,700.
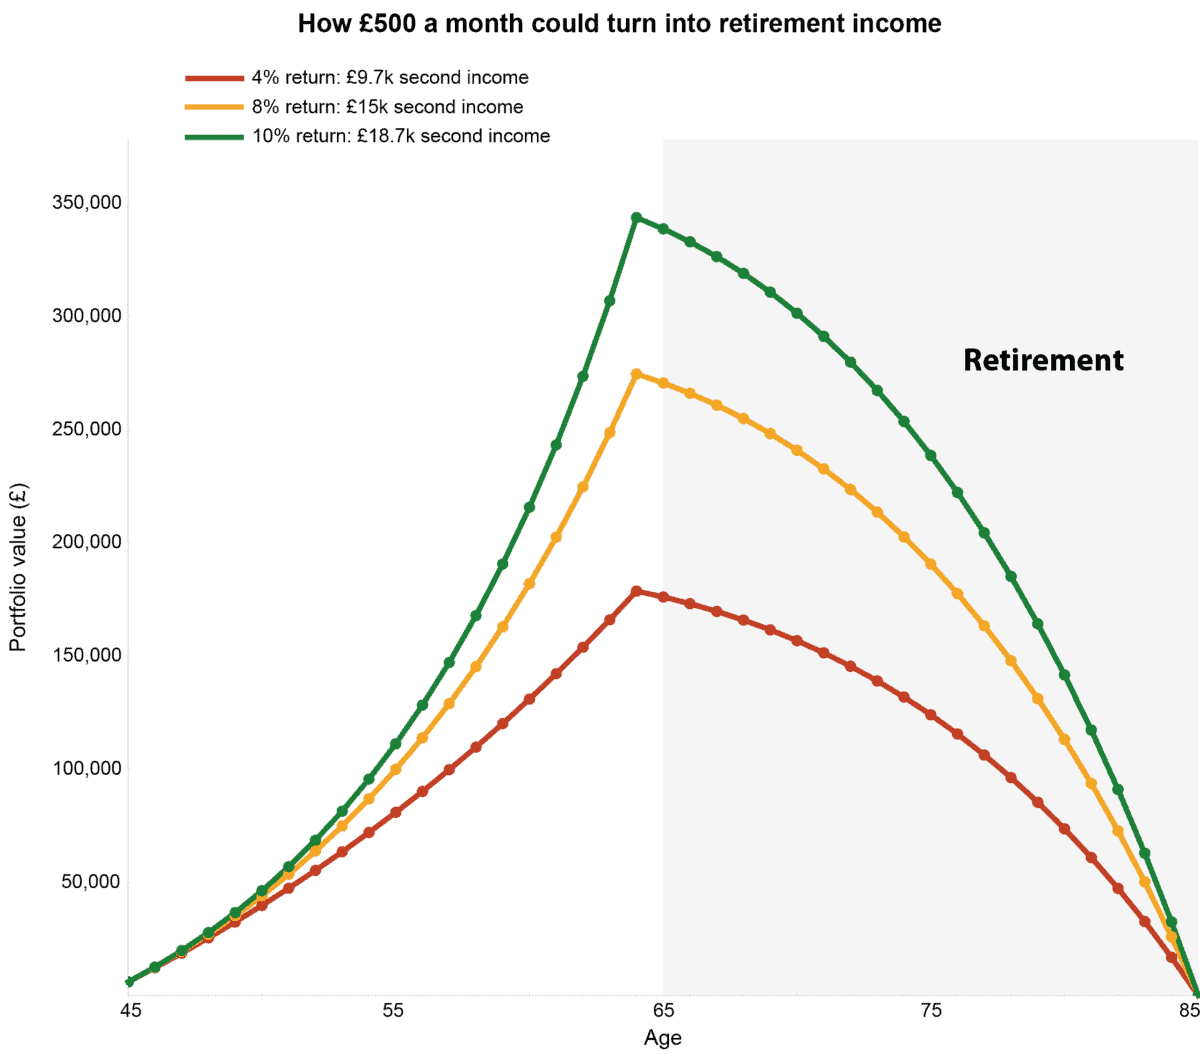
Chart generated by writer
Over a full retirement, that distinction can add as much as tens of hundreds of kilos in additional earnings — or the shortfall that forces harder monetary choices later in life.
And that is the place volatility really turns into necessary.
Market swings aren’t simply noise — they are often alternatives to purchase into stronger future returns at decrease costs. For long-term buyers, that may meaningfully improve the scale of the retirement pot that in the end drives earnings later in life.
Which is why the true danger isn’t volatility itself — it’s failing to reap the benefits of it whereas time remains to be in your aspect.
Falling inventory
One inventory caught up within the current sell-off is Nationwide Grid (LSE: NG.). The share value is down round 12%, which has pushed the dividend yield as much as roughly 4%. It might not look spectacular at first look — however there’s extra to this one than meets the attention.
If the State Pension is beginning to look unsure, this is among the closest issues within the UK market to a personal pension-style earnings stream — predictable, inflation-linked, and constructed on important infrastructure reasonably than financial cycles.
Nationwide Grid operates the electrical energy transmission networks that maintain the UK and elements of the US working. It’s a regulated enterprise, which means returns are largely set by frameworks agreed with regulators. That interprets into extremely seen future earnings streams.
Extra necessary than the beginning yield is how that earnings can develop, with dividends anticipated to trace CPIH over time.
It’s not risk-free. Giant infrastructure initiatives deliver execution challenges, and regulatory shifts or increased rates of interest can weigh on valuations — a part of the explanation the shares have pulled again.
However that’s the place the chance lies. Share value volatility doesn’t essentially mirror volatility within the underlying earnings stream, permitting long-term buyers to construct positions at extra enticing ranges.
Backside line
For me, investing via market cycles is about constructing dependable earnings streams of my very own, reasonably than counting on a State Pension that’s more and more unsure. And with the world quickly electrifying — from EVs to AI-driven knowledge centres — demand for grid infrastructure is barely heading a method.
Nationwide Grid presents a method to faucet into that pattern whereas steadily compounding inflation-linked earnings, utilizing market volatility to lock in higher long-term returns. And it’s simply certainly one of a number of alternatives I’m trying to reap the benefits of proper now.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/