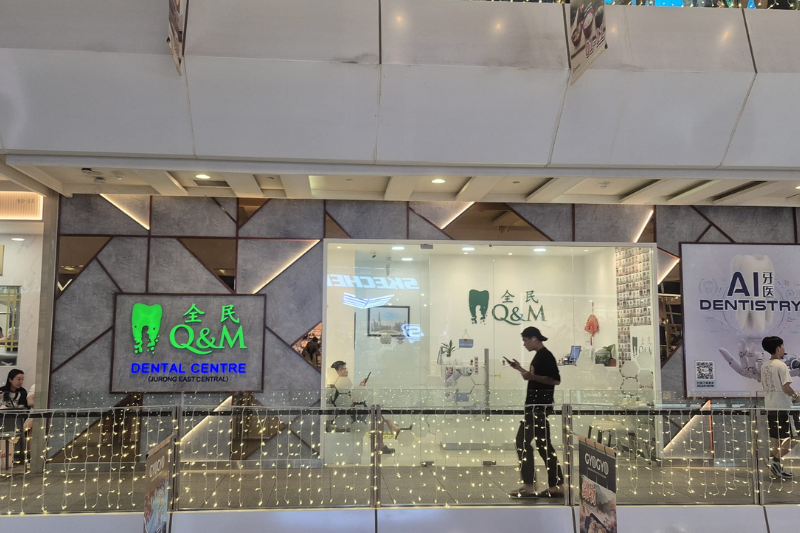
Q&M Dental (Photograph by Rachel)
Take into consideration the services and products you utilize day-after-day.
The bread in your breakfast desk, the curry puff you seize on the MRT station, the dental check-up you schedule each six months.
These on a regular basis necessities are extra than simply line objects in your month-to-month price range; they’re the engines driving a number of established firms listed proper right here on the Singapore Trade (SGX: S68).
For the income-focused investor, the enchantment of those “boring” companies is obvious.
We use them no matter whether or not the Straits Occasions Index (SGX: ^STI) is up or down.
Nonetheless, the true problem is figuring out whether or not these acquainted family names can really ship a dependable stream of passive revenue.
To seek out the reply, now we have to look previous the model and dive into the stability sheet.
When earnings face stress – as they lately have for the three firms under – it’s the money reserve, not the advertising and marketing price range, that ensures your dividend cheque stays within the mail.
You probably have ever purchased a loaf of Gardenia bread, you might be already a buyer of QAF Restricted.
The group is a dominant drive within the regional bakery scene, manufacturing and distributing an enormous array of confectionery merchandise throughout Singapore, Australia, the Philippines, and Malaysia.
The primary half of 2025 (1H2025) was a take a look at of resilience for the bakery big.
QAF reported income of S$306.1 million, a slight 1% dip yr on yr (YoY) as customers tightened their belts.
On the floor, the revenue figures regarded alarming; revenue attributable to house owners tumbled 69% to S$3.9 million.
This sharp drop was largely fueled by an ideal storm of non-cash setbacks, together with S$3.0 million in international forex losses and a S$1.9 million impairment on its Malaysian three way partnership.
But, for dividend seekers, the underlying well being of the enterprise informed a extra optimistic story.
Free money movement really grew by 13% to S$11.5 million, because of disciplined capital spending.
Much more comforting is QAF’s fortress stability sheet.
The corporate holds an enormous web money place of S$162.4 million, with S$188.6 million within the financial institution in opposition to a tiny S$6.9 million in debt.
This money hoard represents practically 29% of the corporate’s S$552 million market capitalisation.
With an unchanged interim dividend of S$0.01 and a trailing yield of 4.9% at a S$1.02 share worth, QAF is successfully utilizing its deep pockets to guard shareholders whereas ready for shopper sentiment to recuperate.
Previous Chang Kee, or OCK, is a Singaporean establishment.
From its humble beginnings as a single stall, it has grown right into a high-margin retail machine well-known for its signature Curry’O.
Story continues
For the six months ended 30 September 2025 (1HFY2025), OCK managed to edge its income up by 0.2% to S$51.9 million.
Nonetheless, the underside line felt the pinch of rising prices, with web revenue declining 19.3% to S$5.0 million and free money movement dropping 20% to S$8.8 million.
The squeeze is a traditional story of contemporary Singaporean enterprise: increased uncooked materials prices and rising wages.
Gross margins narrowed barely to 69.3%, whereas promoting bills climbed 4% as the corporate absorbed the affect of the Progressive Wage Mannequin and the prices of opening new retailers.
Regardless of these headwinds, OCK stays an extremely cash-rich entity.
As of late 2025, the group held S$57.3 million in money in opposition to simply S$1.0 million in debt.
For an organization valued at roughly S$136 million, having 41% of your market worth sitting in chilly, exhausting money offers a big margin of security.
Administration maintained its interim dividend at S$0.01 per share.
Whereas the trailing yield is a extra modest 1.7% at a share worth of S$1.17, the large money cushion means that OCK is well-equipped to navigate a structurally higher-cost setting with out compromising its payout.
As the biggest listed dental healthcare supplier in Singapore, Q&M Dental oversees a sprawling community of 152 dental retailers throughout Singapore, Malaysia, and China.
Its 1H2025 outcomes have been considerably difficult by accounting manoeuvres.
Reported revenue fell 60% to S$3.9 million, however this was primarily resulting from a one-off S$4.4 million accounting loss triggered by reclassifying its subsidiaries.
Once we have a look at the core operations, the enterprise is definitely rising.
Underlying revenue rose 5% to S$8.3 million, supported by a gradual climb in dental income.
In contrast to its friends within the meals business, Q&M is in an aggressive growth section.
The group lately issued S$130 million in notes to fund acquisitions throughout China and the Johor-Singapore Particular Financial Zone.
This transfer has shifted the stability sheet to a web debt place of S$78.5 million.
Presently, Q&M presents a trailing dividend yield of roughly 2.0% based mostly on its S$0.54 share worth and a primary interim dividend of S$0.004.
As a result of the corporate is leaning on leverage to gas its M&A method, the sustainability of its dividend is extra carefully tied to the profitable integration of those new clinics.
It’s a traditional “growth-meets-income” play the place the payout is dependent upon administration’s capacity to show new debt into recent earnings.
These three firms show that even when the financial climate will get uneven, the companies that present our day by day necessities typically have the stamina to maintain paying their traders.
Nonetheless, there’s a clear distinction in how they shield these payouts.
QAF and Previous Chang Kee present a masterclass in stability sheet energy.
Their huge web money positions act as a shock absorber, permitting them to take care of dividends even when web earnings fluctuate.
Q&M Dental, conversely, is buying and selling a few of that security for progress potential, counting on its growth technique to maintain the money flowing.
For dividend traders, the lesson is obvious.
Free money movement is the lifeblood of dividends, however web money is the security web.
While you have a look at the businesses behind your grocery listing, all the time ask if they’ve the monetary stamina to maintain paying you when the market takes a chunk out of their margins.
What when you may gather a gradual revenue from Singapore firms for many years to return? We discovered one in a near-duopoly with 70%+ market share that’s virtually printing cash. Our FREE small-cap report uncovers this “hidden monopoly” benefit (plus 4 different dividend powerhouses) that can maintain paying it doesn’t matter what the market does. Click on right here to seize your copy now.
Comply with us on Fb, Instagram and Telegram for the newest investing information and analyses! Disclosure: Calvina Lee doesn’t personal any of the shares talked about. Chin Hui Leong contributed to the article and doesn’t personal any of the shares talked about.
The publish Flip Your On a regular basis Spending Into Passive Revenue With These Small-Caps appeared first on The Sensible Investor.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/