Manuel V. Pangilinan has planted the flag for Maya’s 2027 market debut, insisting on a Philippine itemizing even when offshore companions pursue Wall Avenue. The goal confirms what inside sources shared with Vantage Level—that Maya was getting ready its itemizing lengthy earlier than the change nudged it to comply with GCash. Recent audited monetary statements filed with the SEC reveal what public buyers will purchase: a core funds turnaround incomes P493 million, however carrying a P30.9-billion legacy deficit and an earnings base nonetheless dwarfed by GCash.
Tycoon Manuel V. Pangilinan has ended market guesswork, setting a 2027 inventory market debut for Maya following GCash’s historic listing.
Talking on Wednesday, October 28, the PLDT and Maya chairman made his stance clear: whereas international companions might eye Wall Avenue, a home itemizing stays non-negotiable.
“I’ve made recognized my choice to the opposite shareholders that in the event that they need to have a Nasdaq itemizing, we have now no objection, however I feel there must be a list right here within the Philippines,” Pangilinan stated.
Pointing to the huge demand behind GCash operator Mynt, he added: “You’ve seen the success of Mynt. Confirmed {that a} high quality firm like Mynt, they’ll appeal to a substantial amount of demand of their shares.” (READ: (Vantage Point) Holiday dividend or market coal? What GCash could deliver by Christmas)
Pangilinan’s goal corroborates what inside sources earlier shared with Vantage Level—that Maya was methodically getting ready for an IPO properly earlier than the Philippine Inventory Trade courted it. Centering a home itemizing ensures native depositors and retailers who fueled Maya’s rise are usually not shut out.
The pivotal query for buyers is easy: what are they shopping for, and at what valuation? The image sharpens with Maya Philippines, Inc.’s Audited Monetary Statements.
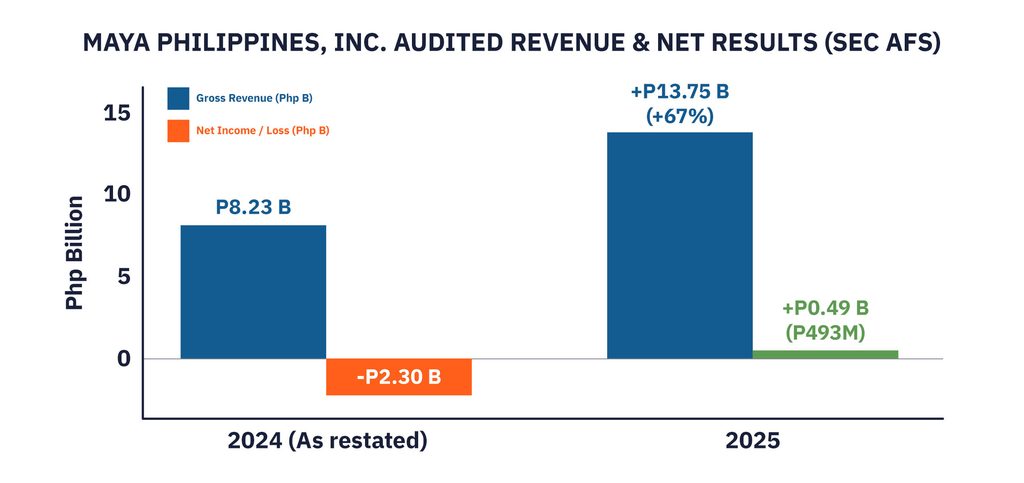
The filings verify an operational pivot: the standalone funds and pockets firm earned P492.97 million in 2025, reversing a restated P2.30-billion loss in 2024. Gross revenues jumped 67% to P13.75 billion, pushed by a 74% surge in service provider service charges to P9.27 billion.
Throughout the broader group, consolidated revenue reached P1.7 billion.
Maya Philippines, Inc. Audited Gross Income & Web Earnings Turnaround (2024–2025).
But the audited stability sheet reveals the steep value of scale. Maya Philippines carries an collected deficit of P30.92 billion as of end-2025. Whereas capital infusions totaling P32.83 billion in paid-up fairness maintain the corporate solvent—leaving internet fairness at P2.23 billion—buyers will look at how this legacy deficit impacts post-listing dividend capability.
Company id is a vital disclosure. Maya Philippines, Inc. operates e-money issuance, service provider buying, and funds infrastructure below Singapore-based mum or dad Voyager Improvements.
Maya Financial institution operates below a separate digital banking constitution. Every arm runs on completely different margins, assumes distinct credit score dangers, and solutions to separate regulators. The itemizing automobile should outline exactly which belongings, liabilities, and earnings streams public shareholders purchase.
Maya’s possession supplies a transparent baseline. First Pacific’s investor disclosures present a formidable register: PLDT anchors the group with roughly 38%, personal fairness agency KKR holds 30%, Tencent carries 15%, and the Worldwide Finance Company accounts for 10%. First Pacific holds 1.6% immediately, leaving 5.4% with different buyers.
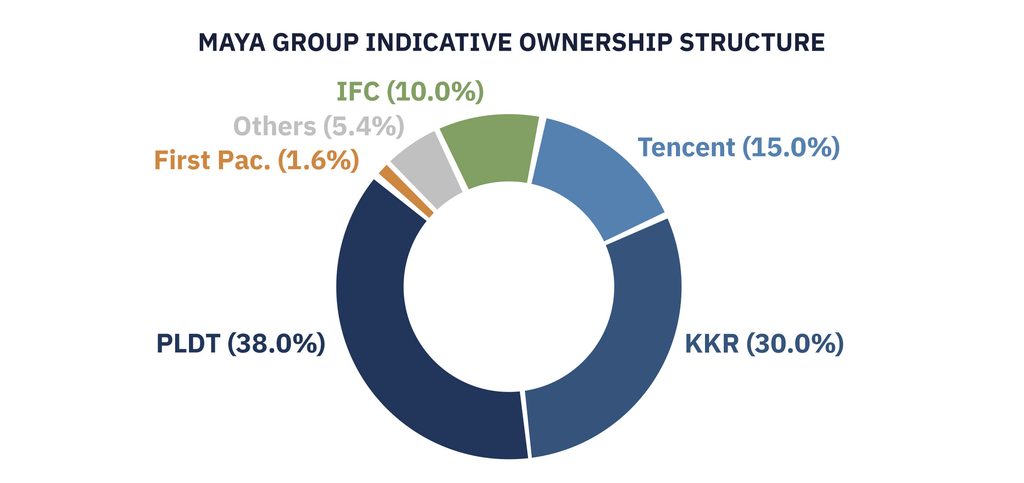
Maya Group Shareholding Construction based mostly on First Pacific investor presentation.
Whereas PLDT supplies home anchor power, international establishments provide capital, know-how, and governance experience. But numerous shareholders carry differing horizons, valuation metrics, and liquidity expectations. When a prospectus seems, distinguishing direct holdings from oblique chains, like First Pacific’s stake through PLDT, might be important to determine voting management.
Working momentum is plain. Liabilities to pockets customers—lively e-money on the platform—jumped 57% to P12.04 billion in 2025, backed by P6.14 billion in belief deposits and P6.72 billion in money.
On retail counters, Maya instructions 53% of registered point-of-sale terminals. On the banking facet, deposits surged 71% to roughly P86 billion by June 2026, whereas mortgage receivables climbed 56% to P39 billion.
But fast enlargement consumes capital. Maya Financial institution’s capital adequacy ratio narrowed from 14.93% in March 2026 to 14.13% in June. This frames a core providing query: how a lot capital might be main funding plowed into the financial institution, and the way a lot will present secondary liquidity to earlier shareholders? Asset high quality additionally warrants scrutiny: PLDT cited a 4.8% gross NPL ratio, versus BSP’s 4.02%, a niche seemingly defined by repo receivables.
Then comes the inevitable benchmark: Mynt. The GCash mum or dad posted P17.23 billion in internet revenue in 2025—roughly ten instances Maya Group’s consolidated revenue and thirty-five instances Maya Philippines’ standalone internet earnings—pulling in one other P10.82 billion in first-half 2026.
Pangilinan conceded that Maya “is probably not the identical scale as Mynt,” however argued it might ship a profitable challenge tailor-made to its dimension.

FFY 2025 Web Earnings Comparability (Maya Group vs. Mynt/GCash).
Maya can’t merely copy GCash’s playbook; it should show how its digital banking constitution and service provider relationships generate superior returns from a tighter base. Evaluating consumer numbers requires self-discipline: Mynt’s 41.5 million month-to-month lively customers and Maya’s 10.7 million financial institution prospects measure completely different populations. The true check might be transaction velocity and buyer retention prices. (READ: (Vantage Point) GCash at P6.60: Did investors finally get their price?)
Furthermore, institutional backing differs. Whereas Maya enjoys established personal fairness and developmental capital, Mynt secured commitments from over 20 international and native cornerstone buyers. Enterprise possession demonstrates confidence at an earlier stage, however cornerstone commitments show an instantaneous willingness to soak up fairness at market clearing costs.
Maya’s turnaround, below the microscope: Income catches up with bills. Maya Philippines Inc., the pockets and funds firm, not Maya Financial institution or consolidated Maya Group.

Income rose 67%; internet revenue margin was 3.6%. Service revenue compensates work for Maya financial institution; related prices stay in bills. Intragroup usually eliminates on consolidation. The primary bridge bar is our substraction, not a company-designated working revenue metric. Values rounded; different internet stability contains curiosity and FX.
Finally, execution hinges on deal construction and pricing self-discipline. Maya has constructed a reputable enterprise with substantial deposits and attain. However because the runway towards 2027 opens, the market’s verdict won’t activate fintech hype.
The decisive check might be whether or not its valuation displays sustainable earnings after credit score losses and funding prices—leaving sufficient room for public shareholders to share within the development they finance. – Rappler.com
This evaluation attracts from Maya Philippines Inc.’s audited monetary statements for 2025, together with restated 2024 comparatives; First Pacific’s October 7, 2026, investor presentation; PLDT’s monetary disclosures; Mynt’s IPO monetary info and cornerstone-investor announcement; and Pangilinan’s reported October 28 remarks. Calculations and interpretations are Vantage Level’s.
Beneath are some Vantage Level items you may need missed:
Click on right here for different Vantage Point articles.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/
https://www.rappler.com/voices/thought-leaders/vantage-point-maya-ipo-meets-accounting-test-manny-pangilinan/