A REIT (actual property funding belief) most likely isn’t the primary place UK buyers are in search of development proper now. With rates of interest nonetheless elevated (and probably on observe to rise later this yr), the sector’s fallen firmly out of vogue.
However whereas share costs have struggled, loads of underlying companies proceed to develop rents, money movement and, in flip, dividends. And in consequence, some now provide among the many highest yields within the inventory market.
Do you have to purchase Tritax Massive Field REIT Plc shares right now?
Earlier than you resolve, please take a second to overview this report first. Regardless of ongoing uncertainties from US tariffs to world conflicts, Mark Rogers and his staff imagine many UK shares nonetheless commerce at substantial reductions, providing savvy buyers loads of potential alternatives to find out about.
That’s why this may very well be an excellent time to safe this precious analysis – Mark’s analysts have scoured the markets to disclose 5 of his favorite long-term ‘Buys’. Please, don’t make any large selections earlier than seeing them.
So which of them have caught my eye as shares to think about in October?
Please notice that tax remedy is determined by the person circumstances of every shopper and could also be topic to alter in future. The content material on this article is supplied for info functions solely. It’s not meant to be, neither does it represent, any type of tax recommendation.
Earnings from healthcare
First on the listing is Major Well being Properties (LSE:PHP), which owns a £6bn portfolio of healthcare buildings throughout the UK and Eire, largely occupied by GPs, the NHS and different medical operators.
Steady healthcare demand even throughout occasions of financial disaster has translated right into a extremely reliable revenue stream. And with the group’s acquisition of Assura finishing its integration, the synergies and anticipated value financial savings at the moment are on observe to reach ahead of initially anticipated.
Nevertheless, buying Assura has added a considerable quantity of debt to the stability sheet, which isn’t precisely superb in an elevated rate of interest surroundings. In response, administration’s begun promoting a few of its lower-priority property property into joint ventures to assist elevate money and convey down the group’s loan-to-value ratio again under 50%.
To date, the technique appears to be working, but when charges climb additional and property costs tumble, the gearing discount course of may show fairly prolonged.
Earnings from storage
Self-storage large Safestore Holdings (LSE:SAFE) can also be navigating uneven waters. But third-quarter revenues had been nonetheless 4.1% greater on a continuing foreign money foundation because of greater UK storage costs and surging demand throughout Spain, Belgium and the Netherlands.
In truth, Safestore’s European markets delivered 11.6% like-for-like development. And with new websites steadily filling up, the corporate may very well be quietly taking market share whereas weaker operators retreat.
However not every little thing’s good. Occupancy has slipped, Paris like-for-like income fell 2.5%, and administration now expects full-year earnings within the decrease half of analyst forecasts.
Throw within the danger of upper rates of interest and administration’s now reviewing the phasing of its 2027 and 2028 UK improvement pipeline.
Nonetheless, analyst groups at each Deutsche Financial institution and Peel Hunt have issued some pretty bullish projections for this enterprise. And as a shareholder, I too imagine that right now’s present challenges could solely be non permanent headwinds.
Earnings from logistics
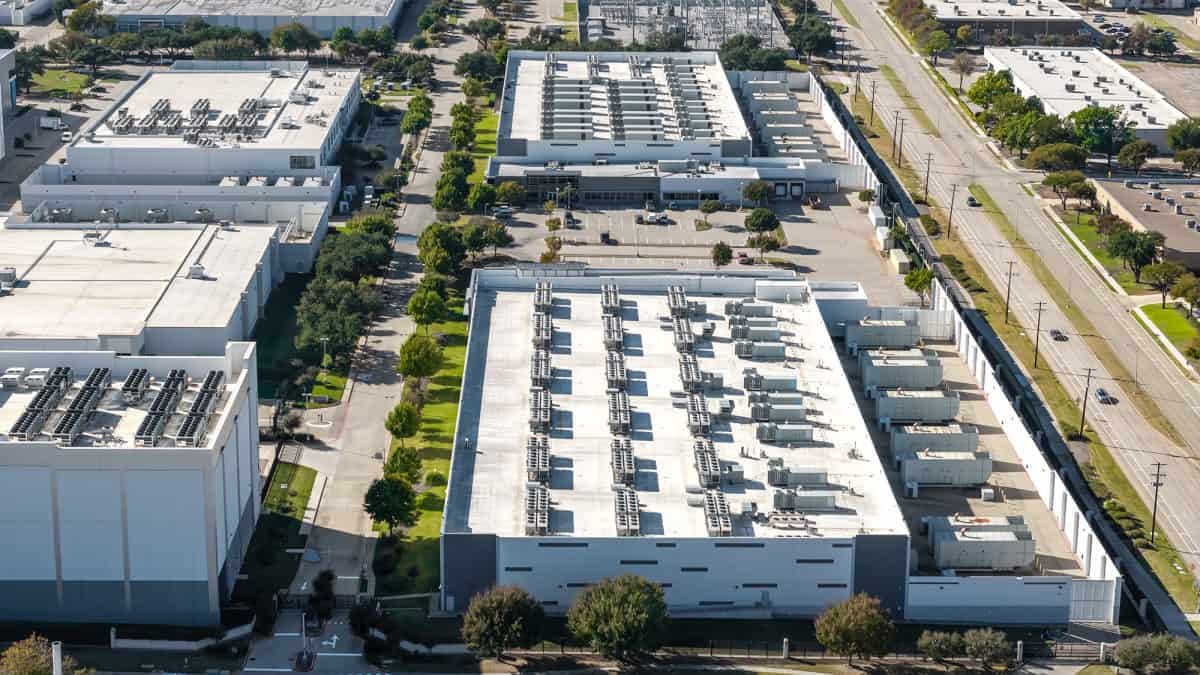
Lastly, there’s Tritax Massive Field (LSE:BBOX), Britain’s largest listed proprietor of huge logistics warehouses.
First-half internet rental revenue jumped 16.2% to £173.3m, whereas recurring adjusted earnings per share rose 7%. And mixed, that supported a 4.4% dividend hike. But with an rising information centre pipeline, there may very well be way more highly effective development on the horizon.
The catch? As soon as once more, greater charges have already pushed property values barely decrease. And growing information centres is pricey, with a current fairness elevate already diluting shareholders, amplifying the influence if these initiatives fail to fulfill efficiency expectations.
But on the identical time, that is one other REIT with some bullish backing from trade consultants, with a mean share value goal of round 199p versus the 140p the shares commerce close to right now.
General, these companies aren’t risk-free. Nevertheless it’s onerous to disregard the truth that every REIT continues to be rising regardless of right now’s hostile surroundings. And that resilience paired with chunky yields is why I believe there is perhaps a considerable passive revenue alternative right here.
What revenue inventory can we like higher than Tritax Massive Field REIT Plc proper now?
One among our Share Advisor analysts has simply launched a model new inventory report that we expect is a must-read for any investor seeking to try to generate potential revenue.
And one of the best bit is you can see if for your self, proper now, completely freed from cost!
No jargon. No onerous promote. Only a clear take a look at an revenue share we expect is value your time.
Zaven Boyrazian owns shares in Safestore Holdings.
https://weblog.passive-income4u.com/create-your-very-own-auto-publish-news-blog-site-and-earn-passive-income-in-just-4-easy-steps/